Access to Finance: Impacts of Publicly Supported Venture Capital and Loan Guarantees
John Rigby
MIOIR
Ronnie Ramlogan
MIOIR
Nesta Working Paper 13/02
January 2013
www.nesta.org.uk/wp13-02
Abstract
This paper is part of the Compendium of Evidence on the Effectiveness of Innovation Policy Intervention. This paper examines government measures to provide firms with access to finance. This covers measures that provide real financial help to firms, i.e. they are a form of financial assistance or subsidy to firms. The two types of policy measures considered are publicly supported venture capital and government backed loan guarantees. Evaluations conducted on these measures employ a range of approaches to assess performance, some of which are simply descriptive, some of which involve comparisons but very few of which attain the level that can control for the selection bias effects that would help to measure the net impacts of policy. One common concern in our analysis of venture capital support and credit guarantees is moral hazard. Evidence shows that even in the most 'careful' schemes borrowers adopt risky strategies. Evaluations of government supported venture capital funds show the importance of design of compensation arrangements in sharing of risk between investing bodies and investees. The a priori assumption, which we ourselves have not made but which others may have done, that these two forms of government backed financial assistance would lead equally to innovation within the firm and the economy is difficult to establish with the evidence provided by the studies evaluated. Moreover, these two forms of financial assistance do have different purposes as they support firms at different stages of their evolution, and we would expect VC support schemes would target firms at the pre-market and more risky phase of development than credit guarantees.
JEL Classification: O38
Keywords: Venture capital; loan guarantee; policy; impact; SMEs; moral hazard.
The Compendium of Evidence on the Effectiveness of Innovation Policy Intervention Project is led by the Manchester Institute of Innovation Research (MIoIR), University of Manchester, and funded by Nesta, an independent charity with the mission to make the UK more innovative. The compendium is organised around 20 innovation policy topics categorised primarily according to their policy objectives. Currently, some of these reports are available. All reports are available at http://www.innovation-policy.org.uk. Also at this location is an online strategic intelligence tool with an extensive list of references that present evidence for the effectiveness of each particular innovation policy objective. Summaries and download links are provided for key references. These can also be reached by clicking in the references in this document.
Author: Dr Ronnie Ramlogan, Manchester Institute of Innovation Research, University of Manchester, Oxford Road, M13 9PL, Manchester, [email protected]
The Nesta Working Paper Series is intended to make available early results of research undertaken or supported by Nesta and its partners in order to elicit comments and suggestions for revisions and to encourage discussion and further debate prior to publication (ISSN 2050-9820). © 2013 by the author(s). Short sections of text, tables and figures may be reproduced without explicit permission provided that full credit is given to the source. The views expressed in this working paper are those of the author(s) and do not necessarily represent those of Nesta.
This report is part of the Compendium of Evidence on the Effectiveness of Innovation Policy Intervention Project led by the Manchester Institute of Innovation Research (MIoIR), University of Manchester. The project is funded by the National Endowment for Science, Technology and the Arts (NESTA) – an independent body with the mission to make the UK more innovative.
The compendium is organised around 20 innovation policy topics categorised primarily according to their policy objectives. Currently, some of these reports are available.
All reports are available at http://www.innovation-policy.org.uk. Also at this location is an online strategic intelligence tool with an extensive list of references that present evidence for the effectiveness of each particular innovation policy objective. Summaries and download links are provided for key references. These can also be reached by clicking in the references in this document.
List of Tables
Executive Summary
This report examines government measures that have been taken to provide firms with access to finance. This covers measures that provide real financial help to firms, i.e. they are a form of financial assistance or subsidy to firms. The two types of policy measures considered are publicly supported venture capital and government backed loan guarantees.
The report first introduces in section two the types of policy measures that we have reviewed while section three explains the scope of sources and material analysed.
In general we find that evaluations conducted on these measures employ a range of approaches to assess performance, some of which are simply descriptive, some of which involve comparisons but very few of which attain the level that can control for the selection bias effects that would help to measure the net impacts of policy.
Very few initiatives are specifically directed at causing innovation as such. Support in the form of venture capital assistance or loan guarantees is intended in the first instance to provide the resources that firms need to grow. Programme designers expect access to finance to lead to increases in turnover and employment which will accompany innovation.
A number of measures seek to promote innovation but in some cases the schemes have been designed and implemented in such a way as to protect firms. This may weaken selection pressures. Few venture capital scheme reviews carry out comparison using matched pairs and account explicitly for selection bias.
Impacts of programmes assessed are usually employment and turnover, with some consideration given to export performance (internationalization) in some schemes. Patenting is also considered in a small number of evaluations.
Some venture capital programmes are very concerned with the creation of systemic effects. Systemic effects are where programmes seek to improve the private capability in the area of investment, i.e. the supply side, with a view to increasing the overall level of funds available for investment, thereby removing or ameliorating the market failure. This is because the investment infrastructure is less easy to preserve and is especially likely to decline in effectiveness during periods of economic difficulty. Some evaluations consider systemic effects on the demand side to be required to solve the problem of the low number of new firms created and the low growth rate of firms.
While some of the evaluations we have examined have been attentive to the impact of finance upon innovation, an issue that we interpreted as at the core of this report, no work has taken the broad and long term economic impacts of the innovations thus funded into account. We therefore do not have a good sense of how important this form of funding is in terms of major impacts upon the economy. More fundamental lessons could be learned therefore about the economic impacts by widening the scope from innovation to commercialisation of innovation. We note that evaluations of schemes that take these effects into account have not been possible to find.
With respect to publicly supported credit guarantee schemes, we note the following points:
- While metrics such as default rate and economic or financial additionality provide evidence about the performance of schemes, better comparisons are not possible as there is no consistent standard for measurement of the schemes.
- Credit guarantee schemes have not been particularly directed to supporting innovation activities and of the studies considered innovation has been the focus of attention of the KOTEC scheme in Korea.
- To the extent that there was credit rationing, credit guarantee schemes have contributed to relaxing this constraint for SMEs in many countries and in different economic climates.
- Credit guarantee schemes help businesses to grow. Several evaluations show a direct causal effect on output (sales) and employment. However the evidence when considered also indicates that some schemes did not impact of firm productivity, R&D or investment intensity. In such circumstances schemes may actually be supporting struggling firms and ultimately stifling innovative forces.
- Finally, one of the more common concerns in our analysis of venture capital support and credit guarantees is the issue of moral hazard. Credit guarantee schemes reduce the incentive and commitment of borrowers to repay loans. Evidence shows that even in the most 'careful' schemes borrowers adopt risky strategies. Moral hazard exists on the part of banks also as studies have shown that in some cases there was less incentive to supervise loans properly. Moral hazard also affects venture capital support measures that have government support. Evaluations of government supported venture capital funds show the importance of the design of the compensation arrangements in the sharing of risk between investing bodies and those organisations in which investments are made.
The a priori assumption, which we ourselves have not made but which others may have done, that these two forms of government backed financial assistance would lead equally to innovation within the firm and the economy is difficult to establish with the evidence provided by the studies we have evaluated. Moreover, these two forms of financial assistance do have different purposes in that they support firms at different stages of their evolution, and we would expect VC support schemes would target firms at the pre-market and more risky phase of development than credit guarantees.
1. Introduction
This report examines government measures that have been taken to provide firms with access to finance. This covers measures that provide real financial help to firms, i.e. they are a form of financial assistance or subsidy to firms. While the mode through which this assistance is given in both equity and loan guarantees is indirect as the assistance comes through organisations partly or wholly private, “access to finance” measures as they are covered by this report refer therefore not to measures that advertise financial support in the sense of giving information about where such finance can be found or in the sense of providing access to potential investors.
In particular the report is concerned with venture capital (equity) and debt finance and measures developed by governments to support their provision with the additional pre-requisite that such initiatives should facilitate innovation. Our report seeks to identify factors key factors of the measures that lead to innovation in order to identify what government policies work in stimulating innovation. These types of measure are not considered as substitutes in that they are intended for and are normally used by firms at different stages of their development. Debt finance is a widely used and relatively inexpensive way through which a firm can raise finance. It tends to be utilised by low risk businesses. Loans and overdrafts are the most common forms of debt finance. Equity finance (especially venture capital) is usually associated with businesses which have great potential for growth but which are high risk[^1]. Such businesses may be at an early stage and lack cash flow and security in order to obtain debt finance. Venture capitalists provide finance in return for an equity stake in the business (BIS 2012). Firms that have greater levels of uncertainty as to their future performance are generally firms that are early stage and small even if there instances of where significant financial support has been provided to larger firms, for example the case of launch aid to Airbus Industrie (WTO 2010). Especially early stage and small firms will usually seek financing in the form of equity investment which carries greater risks for the investor but also greater potential rewards.
1.1. The Midas Touch – Public Policy Rationales
For over decade there have been a range of studies that argued that finance (forms of venture capital and or loans) were important to the economy as a whole because these investments more than any other investments made by large corporates were more effective in generating innovation (Kortum and Lerner 2000; Jeng and Wells 2000). Their analysis suggested that investments made in small firms were far more likely to generate patents than investments made by large corporates. The argument was a seductive one from the point of view of policy makers and venture capitalists seeking to bend policymakers' ears with proposals of hybrid funds.
Our analysis has examined the issue of policy schemes that provide access to finance and do so with the intention of leading to innovation. The report first introduces the types of policy measures that we have reviewed (Section 2) and in Section 3 explains the scope of sources and material analysed. We then report in Section 4 the findings of our review of the studies that have considered the operation of the various measures. In section five we present our lessons and conclusions.
2. Conceptual Background
2.1. Types of finance
This review is concerned with the two major forms of finance -venture capital which is one form of equity financing, and debt finance - that have been used in the support of firms that fail to obtain private investment but which, objectively viewed, may have realistic growth prospects. Policy makers have generally argued that the failure of firms to find finance for growth is a consequence of market failure both on the demand and the supply side. On the demand side it has been argued that firms lack the capacity to locate suitable financial support; and on the supply side it has been argued that the structuring and incentives of the financial sector and indeed recent history of economic decline have led to under provision of the finance to those who might be able to use it effectively. Two main forms of argument have been put forward to explain why such problems exist and why a public policy solution should be found. While the first argument, market failure, provides the essential justifications, we believe that attention should be paid to the institutions of finance themselves and this is why we have included a sub-section on these issues in that understanding of the details of financing decisions (in particular the granting of loans) provides a better basis for the making of public policy.
The Rowlands Report (BIS 2009), which considered how intervention might increase the supply of long term growth capital to SMEs, neatly summarizes the range of financial instruments (products?) that are available for supporting SMEs in the UK. They range from grants and informal lending covering relatively small financing requirements and risk on the one hand to investments with risks of a more substantive nature that can be obtained from private equity or public markets on the other. Figure 1 shows the range of products with the associated risk/return profile.
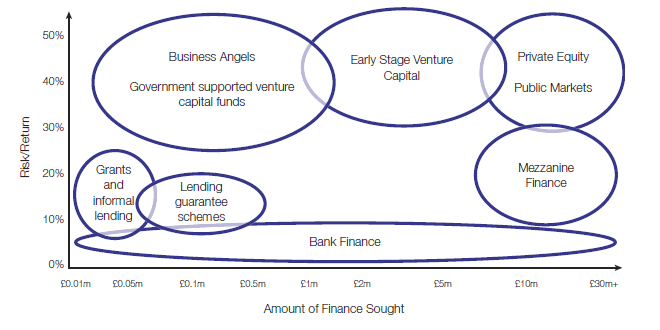
Source: BIS (2009).
Financial support to small firms can be provided in a number of ways, not only in terms of subsidizing equity investments or loans but through other means.
For example, as the NAO (2009, p. 14) report indicates, government support for the financing of firms can include the following types of activity:
- RDA equity and loans funds
- Other government equity investment
- Improving investor readiness
- Promoting investor activity
- Tax schemes (enterprise investment scheme venture capital trusts)
These various forms of support by government comprise indirect financial support; the provision of information and capabilities, and the dissemination of information about specific opportunities for firms and investing companies; the use of the tax system to incentivize usually wealthy individuals to invest in those kinds of firms that might have not have access to the levels of investment that they need. OECD notes these last forms for support are termed public subsidies to private investors (OECD 2007, p. 46). We may also note the significant changes that have occurred in the way in which the industry functions over its relatively short life (Gompers and Lerner 2001).
As indicated above we have chosen to cover publicly supported venture capital and loan guarantees schemes. The relationship between venture capital and innovation has come under much scrutiny in recent years. Most policy makers often assume that venture capital has a positive impact on innovation. However, the empirical literature suggests a very mixed picture. Kortum and Lerner (2000) present a venture capital first account; that is, the presence of venture capital leads to firms innovating. But various other studies (Engel and Keilbach 2007; Hirukawa and Ueda 2008; Caselli et al. 2009; Lahr and Mina 2012; Popov and Roosenboom 2012), all support the hypothesis that venture capital does not foster new innovations but instead invests in already innovative firms. Nevertheless while the direction of causation is yet to be determined, there is still a strong association between venture capital and innovation.
By comparison, in the case of loan guarantees, the relationship with innovation is much more opaque. The overall aim of loan guarantee programmes is to improve levels of bank lending to SMEs. While most programmes do not explicitly have innovation related objectives (e.g. increasing R&D spending), the assumption of indirect effects on innovation and R&D is not implausible. There are however a number of programmes that specifically target innovation and /or R&D. An expert report of 2003 (Report to the European Commission by an Independent Expert Group 2003) for example points to the schemes such as the UK's Small Business Loan Guarantee schemes where, according to the 1999 evaluation, 53% of firms stated they were using the loan to finance new products or services or the Finanzierungsguarantee Gesellschaft Technology Financing Programme in Austria that offers a combination of equity and loan guarantees for technology-oriented SMEs. [^2]
2.2. Rationales for Public Policy Intervention
2.2.1. Venture Capital Support: Market Failures
Why should governments intervene in venture capital markets? The literature recognises two types of market failure arguments that are appropriate in the context of venture capital. The first relates to information asymmetry. Innovators or young high tech firms know much more about their own capacities and the risks of the projects being developed than potential investors. Such information asymmetry leads to adverse selection (Akerlof 1970) and to moral hazard / agency problems (Arrow 1974; Stiglitz and Weiss 1981). Investment funds are therefore in short supply (financing gap) for young firms in high technology sectors seeking resources to facilitate their growth. The second market failure relates to externalities associated with R&D and innovation (Jaffe 1996). Innovation and R&D related projects arguably generate significant social benefits (positive spillovers). To the extent that venture capital investors are deterred from investing in innovation and R&D because they are unable to fully appropriate the returns from their investments there will be under-provision of innovation and hence unrealised social benefits. Both information asymmetry and externality based market failures therefore provide a socially sub optimal outcome resulting in low levels of entrepreneurship. Hence this provides a justification for a public response through subsidising venture capital. But the rationales for government action are not always clear and the results not always positive (Murray 2007).
2.2.2. Market Failures and Access to Equity
As we have noted above, financial support to small firms that are at the earliest stage of their development and in which investment represents a high risk to investors will often receive investment in the form of equity. The term given to such investment in the equity of firms i.e. investment in the firms that involves granting some ownership of the firm from private sources is "private equity” (EKOSGEN 2011). Private equity takes a number of forms depending upon the stage of development of the investee. Classification can be according to the stage at which the investment is made or to reflect the type of actor involved. For example, EKOSGEN uses the following three sub-types of "private equity": angel investing, venture capital, and private equity; while in the BCVA and NESTA framework (British Venture Capital Association and NESTA 2009, p. 26) a fourth category is defined as "friends and family" which takes the place of the very first stage investors. Bessant and Tidd (2007) note five forms for new venture funding: self funding, family and friends, business angels, bank loans and government schemes, but he also notes four main stages: a) initial funding for launch; b) second-round financing for initial development and growth; c) third-round financing for consolidation and growth; d) and maturity and exit. We note that the use of the term private equity often refers to the entire set of investment types and also to the later stage investments where greater investment expertise is brought to bear on the investment and larger amounts of funds are disbursed. The EKOGEN categorization uses the following four stages of investment in its analysis: Early stage; MBO/MBI; Expansion; Other Stage (EKOSGEN 2011, p. 21) while OECD uses four described as follows: Seed; start-up; other early stage; expansion or late stage (OECD 2012).
Figure 2 Main Types of Support: Venture Capital and Credit Guarantees
Venture Capital
* Self-Funding
* Friends and Family
* Angel
* Seed Funding
* Mezzanine
* MBO/MBI
* Further Expansion
Loan Financing
* Direct Loans
* Indirect Loans
2.2.2.1. Equity - Demand Side
The market failures that are held to provide the justification for government involvement have, as we note above, been considered to exist on both demand and supply side. On the demand side, it has been claimed:
- that companies with prospects do, in spite of their potential, fail to "present themselves a investable opportunities due of poor business plans or inadequate business skills,,.. [thereby constraining] their ability to invest.
We also note that:
- small firms that need investment, and which cannot secure loans because of the risks they present to investors, are reluctant to accept equity investment because such investment dilutes the ownership and control of the business. Equity investment right along the investment spectrum from the very early stage through to large private equity investments in established businesses runs such risks of creating conflict with investors³, many of whom will seek payback within a short period of time. Why such conflicts cannot be ruled out through suitable drafting of legal agreements (which would remove the risk and the cause of market failure) is clear: uncertainty in the development of such firms is great and the course of their development cannot be determined.
2.2.2.2. Equity - Supply Side
On the supply side, five reasons are generally given why investors are reluctant to provide investment to firms that might be likely to grow to which a later rationale given by NESTA in 2009 might be added, the sixth in our list:
- Firms that need investment at the early stage are high risk, some will grow, but many will fail and prediction is not accurate such that the costs, which are high and often indivisible, cannot be offset by the returns even for small venture capital investors;
- It has been argued that the historical legacy of very poor and negative performance has altered investor perceptions to the point where they do not reflect reality, leading to an insufficiency of capital for investment by private individuals - (such an argument relies upon the claim that actors are in fact irrational);
- It has also been contended that the investment professionals (as opposed to institutional investors) have begun to focus upon later stage investments where returns are greater, thereby leaving the early stage part of the market for investment funds under resourced[^4]. The predominance of interest at the "higher" end of the investment spectrum is in part owing to the tradition of the so-called "carried interest" whereby investment managers take a profit share proportion to the size of the deal they process, giving them an incentive to work only on the larger deals. The issue is similar to the indivisibility problem noted in a);
- Institutional investors considering exclusively their own returns on their investment do not believe the risks of investing in small firms can ever be high enough to match the benefits of investing in larger firms particularly as realization of the value of illiquid assets of small firms are likely to be low.
- Firms understand better the risks that they face than potential investors, such information asymmetries leading to underinvestment.
- An additional problem that may arise is that markets in which information is exchanged relating to small firms are "thin” ([British Venture Capital Association and NESTA 2009](https://www.nesta.org.uk/report/funding-gaps-to-thin-markets/)). These information asymmetries arise from the infrequency of trading in assets and have the consequence that under investment follows because markets do not set prices reliably.
While action to address the market failures associated with the positive externalities of innovation is broadly justified, the scope for "correction" or the addressing of such market failures of information is as a number of commentators have noted, not clear, and could be very limited. Thus, Brander et al. (2008) feel justified in cautioning against government action here: "Despite these informational market failures, it is highly questionable as to whether government intervention can reasonably resolve the informational problems directly. Governments cannot readily reduce informational asymmetries. One approach to reducing informational asymmetries is to impose strengthened disclosure requirements (as with the much-discussed Sarbanes-Oxley legislation in the U.S.). However, such requirements impose costs and are of questionable merit even for large and established publicly traded corporations. In the entrepreneurial sector, imposing additional disclosure requirements would probably create an excessive and unworkable burden for many entrepreneurial ventures” (Brander et al. 2008, p. 5).
We turn now to the issue of debt finance.
2.2.3. Market Failures and Loan Guarantees
As Lerner (2002) notes, young and high-tech firms in particular, face great difficulties in accessing the loan markets. Indeed the belief that capital markets do not provide adequate funds for new businesses is one of the fundamental rationales behind government loan assistance programs for SMEs (Evans and Jovanovic 1989). Such interventions are based on the widely held perception that the small business sector is an essential element for economic growth; it is an incubator where innovation can arise and new ideas transformed into economically profitable and sustainable business enterprise (Rigby et al. 2012).
There is now a considerable body of theoretical (and empirical work) that attempts to explain credit rationing or justify government intervention in credit markets. This debate is predicated on the assumption that guarantees can lead to an improvement in economic welfare. However for this to be so, there must be a credit market failure and further, any intervention on the part of public authorities must introduce fewer distortions that it resolves (Honohan 2010). A common starting point in relation to credit market failure focuses on the role of information asymmetries between banks and firms. The seminal paper by Stiglitz and Weiss (1981) shows how imperfect information can lead to two problems that result in a failure of the credit market allocation mechanism. The first is the problem of adverse selection. Since the 'quality' of the borrower is unknown to the bank, it is unable to offer a contract that reflects the respective specific level of risk. Increasing price (interest rate) affects the nature of the transaction since those prepared to pay high interest charges may on average be worse risks for the bank. Adverse selection thus impedes the ability of markets to allocated credit using price by attracting high-risk borrowers. The second problem, moral hazard, reduces the ability of prices to clear lending markets because it influences the ex post actions of borrowers as they may be incentivized by any increases in the cost of borrowing to switch to projects with greater risk.
Credit rationing is also likely to occur when banks insist on taking collateral (Cowling and Mitchell 2003; Honohan 2010). Collateral can act as a sorting device (Bester 1985; Besanko and Thakor 1987); it substitutes for information and can limit the potential loss for the lending bank (Boocock and Shariff 2005). It also a strong signal that the entrepreneur believes the project is likely to succeed since only good risk borrowers may be prepared to put up collateral against a loan. However as Vogel and Adams (1997) note, the fact that small firms may be excluded from loans if they do not have sufficient collateral is not an imperfection in the credit market but part of its normal operations. Given their stage of development and even if SMEs have high quality projects, they may be not be able to provide collateral required by bankers.
Honohan (2010) expresses some reservations about the extent to which the adverse information problem or the lack of collateral provides a sufficient justification for intervention. While loan guarantee schemes help SMEs avoid the adverse information problem that leads to credit rationing in Stiglitz-Weiss type of model because of the lower (subsidized) interest rate implied with the guarantee, there is no reason why any guarantor would have an information advantage relative to the bank. Further, although low wealth individuals and groups are unlikely to have sufficient collateral, it is unclear whether improving credit allocation is best instrument to correct for unequal initial endowments. Instead, Honohan (2010) argues that intervention could be justified slightly differently: as a means to kick start SME lending or for offsetting a credit crunch. The former is, in effect a 'learning by doing' argument. SME lending is not well developed because banks lack experience dealing with SMEs, hence face a lengthy loss-making start-up period. Eventually the lenders may acquire sufficient skill and information to continue to lend to the sector without the need for the credit guarantee. In the case of the latter, intervention can be justified when transitory increases in uncertainty lead to information deficiencies and market failure. In such contexts subsidizing the business cycle on a temporary basis might prove to be welfare enhancing.
SME financing issues however arise not solely on the supply side and Roper (2011) points to recent research that highlights demand-side aspects both in terms of the reluctance of SMEs to take advantage of external finance and the 'investment readiness' of many SMEs. He suggests that pecking order models show that firms, due to adverse selection, prefer internal to external finance and even in cases when external funds are necessary, the preference is for debt rather than equity due to the lower information and dilution costs. However the issue of external finance raises further questions about the preparedness of some SMEs, the quality of their business planning as well as financial management and governance systems. The implication is that measures to promote SME finance from the supply-side cannot be considered in isolation.
2.2.4. An Institutionalist Perspective
As Berger and Udell (2004) have noted in relation to loans, the character of and features of the institutional and legal systems under which lending organisations operate have important effects on how small firms (indeed any firm) access credit. Their analysis suggests that the lending infrastructure has powerful influence upon the access to finance of small firms. The importance of apparently irrelevant details of insurance company regulation to name but one aspect of the institutional systems has also been noted by OECD (2004). The problems of business lending that give rise to a need for policy action stem, in part, according to the authors, from the technology of lending. It is also the case that international standards (mainly the Basel Accords) etc provide an important framework that has consequences for the funding of small firms. This framework includes the following (Berger and Udell 2004, p.3):
- Credible accounting standards
- Strong effective and enforceable property rights – stemming from effective commercial laws and codes, effective bankruptcy law,
- The state of security interests which affect the status of and quality of collateral in the context of loan financing, this includes the status of the common law right "lien" upon which mortgages are based
- Restrictions on foreign ownership of financial institutions has, in the case of developing nations, appeared to restrict credit to SMEs
- State ownership of lending institutions
- The role of lending technologies, the types being: financial statement lending; small business credit scoring; asset based lending; factoring; trade credit; relationship lending.
This study is not a however a review of the macro-economic effects of policy on lending as it is a major enquiry of its own. However, we do wish to draw attention to the role played by banking regulatory systems upon lending to small firms as the regulatory requirements of the banking system have important consequences for access to finance (Ayadi 2005).
Public Ownership and Intervention
As we are concerned with public lending, we need to look more closely into the relation between public ownership of lending institutions and policy intervention. While public intervention in private markets for capital and loans can lead to or improve economic efficiency by addressing market failures, it remains the case that public involvement may lead to inefficiencies. In their analysis of the structures and institutions of lending Berger and Udell (2004) note the generally inferior role of publicly owned (“state owned", p. 12) financial institutions may fail to exercise sufficient discipline over the financial investments they make (mainly through lending) to small firms. Such inefficiencies that occur when public organisations are involved in the provision of finance to firms lead to a variety of problems: State-owned institutions may also provide relatively weak monitoring of borrowers and or refrain from aggressive collection procedures as a part of their mandates to subsidize chosen borrowers or because of the lack of market discipline. In nations with substantial state-owned banking sectors there may also be significant spillover effect that discourage privately-owned institutions from SME lending due to "crowding "out effect of subsidized loans from state owned institution or poor credit cultures that are perpetuated by the state-owned presence" (Berger and Udell 2004, p. 12).
3. Scope
3.1. General considerations
This study, like the others in the series, seeks to examine reports and evaluations that comment on and give specific insight into the operation of measures with a view of defining what works in an area of policy. The scope of our search has therefore been to find reports of measures that give such details. To this extent we are limited by the availability of such studies and reports. Our work is based on a review of the academic literature and the grey literature of government sponsored and government and consultant conducted evaluations of such schemes. Our search was divided into two, to focus on equity funding on the one hand and loan guarantees on the other.
Reports of appraisals and evaluations were then examined individually to identify those features of the policies that were effective and those which were not. These findings concerning the features that may play some important role in the effectiveness of the measures overall we term key factors in our analysis. Such factors comprise those aspects of a measure that lead to or are associated with “effectiveness, efficiency and appropriateness” and most likely to lead to or be associated with innovation within the target firms and more broadly.
In this review, as in the other reviews, we have been asked to identify those features that impact upon innovation. Many government measures including many in the area considered here of access to finance aim to give rise to growth and promote competitiveness, but they do not specifically aim to promote innovation as such. In fact few measures seek to promote innovation as their main outcome. We have therefore also sought to look at these measures for access to finance to see where they may lead to in the sense of indirectly causing innovation. This has allowed us to review a greater range of measures and to ensure that we cover measures that, while they may not directly target innovation, nevertheless have an important outcome in terms of promoting innovation. We have thus broadened our focus by considering measures that lead to new firm formation, to the support of firms that have growth or high prospects, and to firms that can be identified as having great propensity to or plans to develop specific intellectual property.
We carry out our assessment of the two forms of finance at the end of the report. We have also been attentive to the issue of capability development and structural issues that affect the demand and supply market failures that give rise, in particular, to the need for hybrid funds – government subsidized equity investments. It has been claimed that a number of measures have real structuring effects in terms of improving the supply of equity capital. Where we have come across strong evidence of such an effect we show how such effects occur. Our review has not however focused explicitly on structuring effects.
We have focused our review on policies implemented at national level although we have taken account of international (e.g. OECD, European Union) initiatives for the support of SME financing through collaborative processes. There remain however, difficulties in pursuing common approaches when it remains the case that different countries employ quite different definitions of private equity / venture capital and loans, as the OECD is well placed to observe (OECD 2012).
3.2. Venture Capital
The scope of our review of evaluations that investigate and report on measures to support the venture capital system with the aim of promoting innovation is made more difficult because of the variety of measures adopted by countries, and recent history, which has created very different conditions for policymaking over a relatively short period of time. This has led to lack of comparability between measures and narrowed the scope for comparison of different periods of time as economic conditions have been varied greatly.
Furthermore, the "venture capital industry" is, as we make clear in our detailed analysis, a misnomer in that there is not a single industry providing capital to firms. Rather there is a series of markets for finance in which there are firms operating across many stages, but in general there are none that operate across all the different stages. Nevertheless, despite the fragmented nature of the market for capital for small businesses, there are some similarities between different business systems and countries for some lessons to be learned and to be applicable generally. We note also that while there are different stages of venture capital, those firms that are served by one stage, if they are successful and continue to grow, will be likely to draw upon successive stages at some point in the future. Thus it is important for policy makers to consider how their actions affect the chain of venture capital provision, not just one particular link.
A consequence for policy making to support the venture capital industry is that, as Meyer (2007) notes, government action can aim at a variety of targets and that while the general aim of government support is, as it is in the area of loan guarantees, to increase the availability of finance to small firms, there are in fact a wide range of options for support and different subsidiary goals, such as increasing social welfare, employment growth, or making changes to perceptions and capabilities of venture capital investors and thereby tackling the supply side problem of lack of investors in the market for venture capital.
3.3. Scope for Credit Guarantee Schemes
Credit Guarantee Schemes (CGSs) originated in Europe in the 19th and early 20th centuries and are now to be found in more than half of all countries, developed and developing, worldwide (Green 2003; World Bank 2008). Different types of schemes have evolved over time. In a large scale survey conducted by the World Bank, Beck et al. (2008) sampled 76 schemes operating in 46 countries and showed that there are large differences in the organizational features (ownership, management and funding structures) and rules of guarantee schemes around the world. Guarantee schemes sometimes focus on specific sectors, regions, or ownership groups, or on young or new technology firms (or even on firms that have been hit by an adverse shock and risk failure). Often there is a subsidiary employment, innovation, or productivity growth objective. Green (2003) identifies five major types of guarantee systems based on their operators: mutual guarantee associations, corporate schemes, those arising from bilateral or multilateral co-operation, schemes operated by NGOs and publicly supported or operated national schemes.
This report focuses on the latter – the publicly supported schemes. These schemes are usually managed by a private sector partner or a government administrative unit or agency. They involve a state subsidy particularly in the initial phases of operation and are well supported by the banking sector as, in the case of loan default, the guarantee is paid directly from the government budget (OECD 2008). The key question to resolve is whether publicly funded credit guarantee schemes are effective instruments for promoting lending to SMEs. The literature does not provide an unequivocal answer. Some authors (Llisterri 1997; Vogel and Adams 1997) have argued that CGSs are costly and give rise to problems of financial sustainability. Others argue that they can open up new lines of credit and can be effective under a well specified framework for their operations (Levitsky 1997). The empirical evidence is slim as there are only few studies that have addressed this issue in a systematic way. In this report we consider the recent evidence from several evaluations that have examined the effectiveness of CGSs in overcoming the main difficulties faced by SMEs in accessing the credit market.
4. Summary of findings
4.1. Review of Measures
We have reviewed and synthesized the evidence of 16 studies of publicly supported venture capital and loan guarantees schemes and these studies are referred to in the tables 1 and 2 below. The tables capture the basic characteristics of the schemes and address their major impacts.
We start in the following subsection by discussing the publicly supported venture capital schemes.
4.2. Publicly Supported Venture Capital: How effective are these initiatives?
4.2.1. Introduction
Our review has made the following assumptions about the policy context in the area of support for venture capital.
- There is a pre-existing financing infrastructure comprising (family and friends, seed angels, and new and established venture capital investments etc) that fails to allocate significant financial resources for growth.
- These barriers give rise to a need for a range of government financial measures or instruments to support companies that do not manage to obtain the finance they need for continued operation and expansion. These financing instruments comprise equity guarantees, co-investment funds and venture capital funds. They can be directed at different parts of the venture capital system; for example, in recent years there has been some emphasis on supporting venture capital by subsidizing business angel networks (BANs), but earlier efforts to support small firms in need of capital were directed at increasing the supply of slightly later stage venture capital.
- These various instruments developed by government often in conjunction with the private sector support different parts of the venture capital process, and they also reflect the political and economic priorities of government. These priorities can be addressed through geographical and sectoral targeting and a focus on size of firm supported.
- Additionally, the instruments may set a risk level for the investment although this will be related to the financial partner, the type of instrument used and the priorities.
Our review of the impact of such measures seeks to answer the following questions which represent a set of ever more stringent tests of the effectiveness of the measures: a) do the measures increase the provision of equity capital for small firms; b) does the availability of finance result in changes within the firm that receives the financial assistance in terms of improvements in productivity, employment, and export performance; c) what level of additionality occur (if this has been measured) within the firm; d) what impacts upon innovation have arisen within the firm and beyond it (if measured); and e) finally, what impacts have occurred at the system level. The following discussion centres on these issues and attempts to indicate, for each test, relevant explanatory factors. These explanatory factors may include the venture capital segment that is the subject of the measures (i.e. Angel, Seed, Early Stage, Formative, Later Stage) but it may also include the management, organisation and operation of the measures, as well as business sector focus and geographical location of the measure. As we note later on in our comments on the systemic effects of venture capital support by government, the conditions faced by firms seeking financial support for growth and expansion (across the whole spectrum of venture capital) have varied enormously over the last two decades and this has made it difficult for policy makers to decide on policy goals and difficult for evaluators to determine impacts. The period has been once where the whole market for venture capital has boomed, with strong demand and strong supply. But there have been periods when there has been very little demand for resources and a very weak supply, in the so-called "nuclear winter" between 2001 and 2003, the period immediately following the dot-com bust. But there have also been periods when part of the market has worked well but other parts have fared badly (Yong-Protzel et al. 2007). During the 2004-2006 there was a "buy-out" boom where later stage capital was in good supply, but early stage firms were not well-served.
4.2.2. Easing Access to Finance
The provision of financial support by government through its various programmes of venture capital investment should allow more firms to access finance that are affected by market failures. Our review is clear that in this regard, the evaluations indicate that such measures have increased the availability of finance to firms. This is not to say that measures necessarily lead to additionality however.
We note however that access to venture capital appears to be very dependent upon proximity to venture capital firms and major urban centres. Those examining the problem of venture capital on a regional basis have become aware of the distinct decline in the availability of venture capital with increasing distance from major cities and in particular capital cities. This phenomenon of the “stickiness” of venture capital suggests that there are, within the regions, clear market failures for investment in the early stages of equity capital investment to which regional VC funds, rather than general, national or international commercial funds, are the answer Sunley et al. (2005). A paper comparing clustered with dispersed support to VC but without reporting findings on a specific scheme is Martin et al. (2002). Munari (2010) has examined the UK and has noted that the regional variations in venture capital are significant. His recommendation for policy is that government initiatives should target regional disparities to prevent those differences from being perpetuated and indeed made worse; but this is problematic because regions are by definition, distant from capital cities. The review of the UK's recent policy for regional venture capital - the Regional Venture Capital Funds - reveals very poor performance with the policy implication that funds should not be “constrained to regions” at all (Reid and Nightingale 2011, p. 20), although the analysis by Lerner et al. (2011) suggests that the very poor performance of the UK funds is not attributable entirely to the regional focus of funds.
While we are dealing with VC funding in this section, we feel we should note that the problem of financing business growth in the regions is likely to be one of ensuring that the right forms of financial assistance are available that match the local conditions. Thus, in areas where new firm formation produces firms that generally are avoided by VC organisations, debt financing for growth may be more suitable than government backed VC funds.
A further general point about the availability of venture capital is made in the study by Sunley et al. (2005). The authors suggest that access to finance is most critical for the firms at the earliest stages - just beyond angel investing stage. The initial policy response of the EU to financing at this level largely ignored this area (Mason and Harrison 1999). The equity gap that most affects technology firms (the subject of the study by Sunley et al. in their paper) is within the range from £250k to £750K[^5]. The implication of this finding is that the then cap on the investments made by the regional funds in the UK context should be raised to £750k.
Observation of the importance of the public sector within the overall provision of venture capital in the regions (mainly beyond London and the South East of England) in the UK has led Mason and Pierrakis (2009) to doubt the efficacy of public provision of venture capital without also addressing the demand side. One of their main conclusions is that regional funds are not likely to yield returns and generate growth unless the supply of high growth firms is enhanced, which will require greater use of demand side initiatives such of the kind operated in the US by the US Small Business Service (the Small Business Innovation Research (SBIR) Program) or in the UK the Technology Strategy Board's Small Business Research Initiative (SBRI).
4.2.3. Impacts within the Firm: Productivity, Employment, Turnover, Exports
It is notable that amongst the measures we have reviewed there are some which, while attempting to provide venture capital to firms have been directed towards the creation and preservation of employment.
It is perhaps not surprising that in the economy which has been longest in recession covered by this study - the Japanese economy – venture capital measures have been used to promote employment rather than growth. In Japan, the venture capital support has been modelled on the US Small Business Investment Company (SBIC) model[^6] but was found to have a relatively high bureaucratic load and few major investors are involved. The Japanese system has seen little targeting of small firms and potentially high growth firms, and VC funding has been used generally as recession protection insurance rather than as an attempt to create Schumpeterian "destruction" (Schaede 2005). In Canada, venture capital funding schemes have also been developed to support the economy in times of economic stress although the example covered by Ayayi (2004) is of a labour union sponsored scheme, not a government scheme.
Other schemes reviewed focus on such objectives as technology or output growth rather than employment. The Scottish Co-Investment Fund (SCF) evaluation has noted that the support given by co-investment has had greater effect on turnover than on employment (Centre for Strategy & Evaluation Services 2008). The study by Murray (1998) however notes that investment in high technology firms has had a greater impact on employment than in non-high technology firms. This latter point is an interesting finding and is not consistent with the view, very widely held, that high growth firms – so-called gazelles - can be found in all sectors.
Studies not on a specific measure but instead companies that received various forms of private VC funding suggest further important focusing and selection mechanisms. In his study of firms in the CorpTech database, LiPuma (2006) notes the effect whereby venture capital investment restricts a firm's operation overseas. It may be the case that - and there are good ex ante reasons for believing this to be likely – venture capital places requirements upon firms that might not be present otherwise, for example, to commercialize their product more quickly. Such an effect, which would arise when the investing company seeks to secure a return upon its investment, would encourage firms to focus upon their home markets, rather than to internationalize.
Two recent studies undertake a quantitative comparative assessment of impacts of publicly supported venture capital on firms. The first, using an instrumental variables estimator to control for selection bias is by Brander et al. (2010) who examined the differences between Canadian public (GVC) and private venture (PVC) capital investment on a range of outcomes related to value creation, competitive effects, and innovation. The study concludes that enterprises funded by GVCs tend to underperform on most outcome measures. They are less likely to have successful exits and, in particular, are much less likely to have IPOs on major exchanges. Furthermore, they generate lower exit values when they do have a successful exit. The GVCs invest less in high technology industries, and their enterprises generate fewer patents (even after controlling for industry selection). The study suggests there is no evidence that GVCs increase employment or competition. The second study along similar lines, Grilli and Murtinu (2012), examines the impacts of GVC versus independent venture capital (IVC) in a multi European country context. This study suggests GVC investment has no sizeable or significant effect on either the sales or employee/firm growth of European high-tech start-ups observed from 1993 to 2010 although there is some evidence of a sales impact when funding is syndicated but the governmental investor is subordinate to the private interest.
4.2.4. The Additionality Dimension
Evaluations that attempt to determine whether there is additionality at the level of the firm are not common and we were able to locate just seven that draw some form of contrast between firms supported and not supported. The study of Flanders support to Business Angel Networks (BANs) (Collewaert et al. 2008) uses a matching approach and is therefore more likely to discover the presence of a genuine net impact of the government initiative. The evaluation is inconclusive as regards performance improvements, in that short term impacts are negative although longer term ones may be positive. The study does not specifically focus upon innovation within the investee firms.
An interim evaluation of the Regional Venture Capital and Early Growth Funds (CI Research 2009) found from business and stakeholder surveys that both programmes provided funds to firms that were unlikely to attract private sector equity finance. The evaluation found businesses reported a wide range of benefits including the introduction of new products and services, entry into export markets and advice and guidance from Fund Managers. The majority of businesses experienced growth in employment and turnover, and attributed this to the investment of public funds.
4.2.5. The Innovation Impact
Very few of the evaluations that we have found are concerned directly or even indirectly with the innovation impact of venture capital support.
The review by Murray (1998) of the hybrid funds of the European Seed Capital Fund suggests that commercial funds were more likely to lead to innovation than regional public funds[^7]. A subsidiary goal of the commercial funds reviewed in this study was that they sought to invest in new technology based firms. The evaluation did not look at the performance of the funds in relation to innovation specifically. However, the study reveals that investments in high technology firms were more common in the general commercial funds than in the regional funds, despite the fact that the regional funds believed that they were investing more in technology firms than the commercial firms. Amongst the regional firms, the overall number of investments in firms that might be assumed to be high technology and therefore innovative was around 10% of the total firms. Importantly, the study found that higher technology firms (of which a majority asked for private instead of public money) were more likely to achieve higher growth in employment.
As we have noted above, the Japanese SBIC has sought to promote employment rather than innovation (Schaede 2005), and there are a significant number of schemes to increase the provision of venture capital that seek to support existing businesses rather than to create to sustain very new firms to deliver create innovation or growth. Policy makers in many countries, Japan is a good example but Canada (Ayayi 2004) is also a good case, have used venture capital funding instruments to support existing firms and have developed their schemes in periods of economic crisis. These policies protect existing firms rather than creating new firms.
Where there are schemes that focus on firms where technology innovation is likely to occur, one would expect these to give rise to innovation. However, there are confusing findings on this point. The review of Australian Pre-Seed Fund established in 2002, previously an Innovation Investment Fund (Australia) which had been operating since 1997 (Cumming 2007) has found that its investments are no more likely to be made in innovative and high technology companies than the average for a fund of this size, in spite of the fact that the rules of the fund management require investments into firms that are capitalizing upon and exploiting the scientific discoveries that have been made in universities and public laboratories or be connected to a grant (and that such firms be controlled by a university, public sector research agency or qualifying researcher or that they use intellectual property that is at least 50% owned by a university, public sector research agency or qualifying researcher). That a fund targeting what should be high technology firms should in practice give no more support to high technology firms than the typical fund may suggest problems with the management and operation of the fund (Jääskeläinen et al. 2007).
There is further a view that receives support from a number of writers that capital does not lead to innovation but that it merely supports commercialisation of existing innovations. This claim – that financial resources follow innovation rather than leading to it – is an important one and it receives support from both economic modellers and scholars of the innovation process. Firstly, the economic modelling done by Engel and Keilbach (2007) suggests that VC investment leads not to innovation but to commercialisation, a view supported by Hellmann and Puri (2000). The difficulty is that these studies involve patent counts as the measure of innovation, also echoed by more recent studies, see for example Snieska and Venckuviene (2011). Engel and Keilbach's (2007) approach uses matching to ensure comparison of the treatment effect with relevant non-treated firms.
This approach is strongly supported by research by other qualitative researchers looking at innovation and finance. A recent paper by Tether and Stigliani (2012) suggests that "innovation", in terms of the creation of new ideas, if not products and processes, within the firm results less from the provision of financial capital and far more from the application of the creative and networking capabilities of a firm's owners.
As we have noted above, the use of patent counts as the measure of innovation is problematic and may not be the best way of detecting whether venture capital causes innovation. As Engel and Keilbach (2007) accept, in their study of firms that received venture capital, those firms that received investment were ones that already had innovations in the form of patents. This, they say, suggests that venture capitalists choose to invest in firms that already have innovations rather than in firms that have yet to innovate but may be on the point of doing so. From the point of view of venture capitalists, a firm's intellectual property in the form of patents is an indicator of potential return that is likely to be a more closely associated with future performance than say a promise from the owners of the firm of future innovation activity.
4.2.6. Fund Level Impacts
The most important evaluation of UK schemes have examined the effectiveness of public support at the scheme level rather than at the level of the individual firm (NAO 2009; Lerner et al. 2011). These evaluations indicate that public funds are generally smaller in size and that they invest in fewer firms and the average size of their investments are smaller. Furthermore they realize gains (exits) less often and overall, their returns are significantly lower with the average IRR being 10 percentage points lower than the "average private fund in the UK and 6 percentage points lower in the US” although the large public-private returns gap diminishes slightly when controls for vintage year are introduced.
4.2.7. Systemic Impacts
As has been argued by the British Venture Capital Association and NESTA (2009), an important but hitherto neglected aspect of the design of studies that investigate VC funding policies of governments is that of the wider impacts of VC funding upon the economy and upon recipient firms. This approach is different from and could be said to run counter to the emphasis placed by the "inputs to the firm" perspective adopted by many finance oriented reviews of the VC capital policies of governments. However, few evaluations of programmes have been commissioned to investigate these broader – beyond input – effects of policy that are designated "entrepreneurship capital” within the capabilities perspective (Audretsch et al. 2008), or which investigate economy wide impacts on productivity growth.
The ideal case of the development through initial government support of an operational venture capital market that can ultimately function without support is that of Israel. Here, success has been attributed to the strong cultural and emotional bond with the US and the strong links between Israeli based entrepreneurs and foreign investors (Avnimelech and Teubal 2008; Jeng and Wells 2000). By contrast, Cumming (2011) argues that the systemic problems of VC investment generally are the result of government intervention in the market and that these problems do not constitute a rationale for investment but a warning against further government intervention.
Many of the government interventions that have been covered here seek to make immediate impacts upon firms and at the same time to achieve systemic change to the market for venture capital. The nature of changes to the system varies but the overall effect which is sought is that venture capital becomes more widely available and that the market failures on the supply side are reduced or removed.
The evaluation by Ryan (1990) of the Australian MIC Programme (Management and Investment Companies) stresses that the market for private equity is not a single homogenous market for risk capital and that the impact of any policy needs to be understood in terms of its outcome for the system as a whole.
4.2.7.1. Other System Level concerns
A study carried out by Jääskeläinen et al. (2007) examines, using simulation, the characteristics of hybrid funds (profit distribution and compensation structures) and attempt to define and identify the conditions under which early stage CV hybrid funds may operate profitably. The research has important conclusions for the operation of venture capital funds supported by government. One of their most important conclusions is that in the conditions of moderate and significant market failure, no design of hybrid fund of any kind can be achieved and that other measures beyond financing must be adopted: thus, schemes will fail "in the most difficult and problematic areas unless these schemes also have the effect of improving the quality of investors and subsequent gross returns". The authors continue: "As a consequence, governments will not be able to rely on such programs alone to improve the supply of early-stage finance. They are likely to have to address other related issues, in particular improving the framework conditions that will encourage the participation of more skilled and experienced entrepreneurs in key technology sectors” (Jääskeläinen et al. 2007, p. 927).
The review by Maula and Murray (2003) considers the connection between venture capital funding and other forms of support, such as capability building amongst investee firms, but also the R&D grant system and the export credit guarantee system. In Finland this system is operated by Finnerva PLC.
Other work (not peer reviewed) suggests the importance of the system as a whole and the need to consider a systemic approach to the development of policies to support the provision of venture capital (Meyer 2007) including the demand side (Mason and Pierrakis 2009).
Table 1. Reviews of Venture Capital Support Measures
Table 2. Review of Loan Guarantee Support Measures
4.3. Loan Guarantees: How effective are CGS?
4.3.1. Introduction
The primary purpose of guarantee schemes is to expand availability of credit to SMEs. There is a general perception that SMEs are seriously disadvantaged in financial markets. With fewer assets and lacking a track record, small firms experience tighter financial constraints from the banking sector compared to other firms (Zecchini and Ventura 2009). In a debate spanning almost 4 decades, various authors ([Green 2003](https://www.unido.org