This report makes the case for innovation to make childcare more affordable, more accessible and more flexible to parents and families.
This report makes the case for innovation to make childcare more affordable, more accessible and more flexible to parents and families.
Key findings
- Despite successive governments’ attempts to improve the childcare market in the UK, it is still not working for parents, families and children.
- Existing and new innovations have the potential to be scaled and address the key pinch points of affordability, accessibility and flexibility in the childcare market.
- Four areas of innovation that have the greatest potential are co-produced childcare, provider collaboration, new forms of investment and funding and development of informal childcare social networks.
The political debate over childcare in the UK has increased in intensity and in urgency in recent years. This is hardly surprising given the central role that childcare provision plays both in improving life chances for children themselves and in enabling parents to work.
While childcare places have increased dramatically over the last two decades, there remains an acute need to provide affordable, flexible, high-quality childcare for every family that needs it. Gaps in the provision of childcare are most in need in deprived areas and if we are going to meet the demand for childcare provision, we need to look to a range of new models that can address the issue of affordability for parents, low profit margins for providers, gaps in provision and a lack of flexibility in delivery.
This report details a number of innovations, both from the UK and globally, that show potential to address the key issues of flexibility, accessibility and affordability of high quality childcare.
Authors
Jill Rutter, Family and Childcare Trust
ACKNOWLEDGEMENTS
We would like to thank Max Wind-Cowie, Ellen Broome and Duncan Lugton for their contributions and help over the course of this project. At Nesta, we would like to thank Matt Stokes, Juan Escallón, Helen Goulden, Helen Durham, Annette Holman and Tom Symons.
Nesta...
Nesta is an innovation charity with a mission to help people and organisations bring great ideas to life.
We are dedicated to supporting ideas that can help improve all our lives, with activities ranging from early-stage investment to in-depth research and practical programmes.
Nesta is a registered charity in England and Wales with company number 7706036 and charity number 1144091. Registered as a charity in Scotland number SCO42833. Registered office: 1 Plough Place, London, EC4A 1DE.
www.nesta.org.uk
©Nesta 2016
- ACKNOWLEDGEMENTS
- FOREWORD
- SECTION ONE: INTRODUCTION
- SECTION TWO: THE PINCH POINTS
- SECTION THREE: AFFORDABILITY
- SECTION FOUR: ACCESSIBILITY
- SECTION FIVE: FLEXIBILITY
- HOLIDAY CHILDCARE
- FILLING THE GAPS WHERE PARENTS
- DEPENDENCE ON INFORMAL CHILDCARE
- FORMAL CHILDCARE FOR PARENTS
- FIGURE 5:
- INNOVATIONS IN FLEXIBILITY
- CHILDCARE SOCIAL NETWORK
- IMPACT
- BARRIERS TO ADOPTION
- NEXT STEPS
- CARE CREDITS
- CASE STUDY
- IMPACT
- BARRIERS TO ADOPTION
- NEXT STEPS
- CONCLUSIONS ON FLEXIBILITY
- SECTION SIX:
- BIBLIOGRAPHY
FOREWORD
The political debate over childcare in the UK has increased in intensity and in urgency in recent years. This is hardly surprising given the central role that childcare provision plays both in improving life chances for children themselves and in enabling parents to work.
While childcare places have increased dramatically over the last two decades, there remains an acute need to provide affordable, flexible, high-quality childcare for every family that needs it. Gaps in the provision of childcare are most in need in deprived areas and if we are going to meet the demand for childcare provision, we need to look to a range of new models that can address the issue of affordability for parents, low profit margins for providers, gaps in provision and a lack of flexibility in delivery.
This report details a number of innovations, both from the UK and globally, that show potential to address the key issues of flexibility, accessibility and affordability of high quality childcare.
Helen Goulden, Executive Director, Nesta
SECTION ONE: INTRODUCTION
ABOUT THIS REPORT
This report is the product of a two-part research collaboration between the Family and Childcare Trust and Nesta. The Family and Childcare Trust initially undertook a systematic, situational analysis of the UK's childcare market in order to understand where pinch points and problems exist. From this analysis, we identified three major pinch points that adversely affect parental access to childcare and, therefore, to the workforce. These are affordability, accessibility and flexibility.
We then used desk-based research and international comparisons to develop a long-list of potentially useful innovations that could help to address these key barriers and correct the market in favour of parents and families.
Finally, we used structured engagement with experts and practitioners in the field - alongside a matrix analysis that tested potential innovations against a range of factors including attitudinal impact on parents - in order to test these solutions and focus down into a shortlist of workable, good value interventions that hold the potential to broaden and deepen access:
- Co-produced childcare: bringing more appropriately-trained volunteers and parents into formal childcare settings in order to reduce staffing costs, expand the social mix of adults in childcare settings and reduce costs to parents and families.
- Provider collaboration: bringing childcare providers together to share premises, facilities and back-office staff to reduce these input costs, as well as to develop new forms of provision such as childminder hubs and childcare on domestic premises.
- New forms of investment and funding: leveraging new investment into the child-care market - particularly in deprived areas.
- Informal childcare social networks: increasing participation in reciprocal informal childcare networks through care credits; expanding the reach and take-up of digital platforms to match supply and demand easily and flexibly.
The innovations that are proposed here are a mixture of completely new ideas with no current presence in the UK system and existing small-scale interventions with the potential to grow into bigger and more comprehensive solutions. As well as extensive engagement with practitioners and experts in the sector, they build on the Family and Childcare Trust's own analysis and expertise and on a broad and deep hinterland in policy and practice.
Most of these innovations will require multi-faceted and multi-layered support in order to succeed - from central and local government, from social and private entrepreneurs and from civil society. So we conclude by laying out specific recommendations, aimed primarily at local and central government - ideas for change which our analysis suggests would radically improve the affordability, accessibility and flexibility of childcare.
DEFINITIONS OF CHILDCARE
It is important to lay out some definitions which have been used in this report.
Formal childcare for the under-fives is administered by a range of providers which include day nurseries and childminders, with both offering care for up to ten hours every day, over 48-50 weeks of the year. Parents may also use part-time childcare offered in pre-schools or sessional crèches. There are about 400 state nursery schools in England that offer early education for three and four year olds and sometimes two year olds. Early education is also provided in nursery and reception classes in primary schools. Parents frequently use multiple forms of childcare in order to provide their children with a holistic package of care.
When children start compulsory education, many parents use out-of-school and holiday clubs. In England, in 2013, some 6 per cent of families with children under 15 used breakfast clubs and 36 per cent used after-school clubs (DfE, 2014a). Other families use childminders to pick up their children after school.
Children of secondary school age still require some care and supervision, particularly during the school holidays, although activities for this age group are not usually described as childcare in everyday speech. Moreover, most out-of-school clubs and play schemes do not provide activities that are appropriate for them. Instead, many parents of 11-14 year olds may use arts, sports and leisure activities as de facto forms of childcare.
WHERE WE ARE NOW1
The political debate over childcare in the UK has increased in intensity and in urgency in recent years. This is hardly surprising given the central role that childcare provision plays both in improving life chances for children themselves and in enabling workplace participation for parents. Today, about 80 per cent of families with children under 15 use childcare in England and nearly 60 per cent of them pay for it (DfE, 2014a).
Childcare provision is a crucial part of a modern state's infrastructure: it enables parents to work, improves children's outcomes and helps narrow the gap between disadvantaged children and their peers. This essential service also enables businesses and public services to function. Without affordable childcare provision, the skills of working parents are lost and families are forced to depend on benefits, rather than contribute to the economy as taxpayers. As a consequence, all recent governments have put resources into improving childcare in the UK.
Over the last 15 years much progress has been made to increase the affordability and availability of childcare in the UK. Parents currently receive help with their childcare costs through the childcare element of Working Tax Credit, vouchers and free nursery education. Over the next two years, the amount of help that parents receive is set to increase, with the changes set out in Table 1. Public subsidies for childcare are at an all-time high, amounting to £5 billion in the UK in 2015 (House of Lords Select Committee on Affordable Childcare, 2015).
TABLE 1:
Summary of sources of help with childcare costs in England
| LEVEL OF SUPPORT | RECIPIENT GROUP | DATE AVAILABLE |
|---|---|---|
| Childcare element of Working Tax Credit 70 per cent of childcare costs up to a maximum of £175 per week for 1 child or £300 per week for two or more children. | About 400,000 low-income working families. | Presently available |
| Universal Credit 85 per cent of childcare costs, with same maximum levels as Working Tax Credit. | Low-income working parents. | Currently being rolled out |
| Childcare vouchers Worth up to £55 per week for basic rate taxpayers. | Working parents, but not self-employed. Usually excludes those receiving tax credits. | Presently available, but will not accept new applicants after 2016. |
| Tax-Free Childcare 20 per cent of childcare costs up to a maximum of £2,000 per year. Families of disabled children receive help with 40 per cent of costs to a maximum of £4,000 per year. | Parents not in receipt of tax credits/Universal Credit, where each parent earns, on average, a weekly minimum equivalent to 16 hours at national minimum wage (NMW) or national living wage (NLW), and less than £100,000 per year. | From early 2017 |
| Care to Learn £175 per week in London and £160 per week outside London. | Parents under 20 at school or in further education. | Presently available |
| Further education Discretionary Learner Fund Discretionary | Parents over 20 in further education. | Presently available |
| Higher Education Childcare Grant Up to £155.24 per week for 1 child; up to £266.15 per week for two or more children. | Full-time higher education students with children. | Presently available |
| Free early education 570 hours per year, usually 15 hours per week in term time. | All 3 and 4 year olds and the 40 per cent most income-deprived two year olds. | Presently available |
CURRENT PROVISION
But despite good intentions and active policy interventions, major problems remain in Britain's childcare market. These issues impact widely on the quality, availability and price of childcare - and, as a result, on the wellbeing of families and on the British economy as a whole. This report, produced by the Family and Childcare Trust on behalf of Nesta, takes a structural look at the British childcare market in order to understand what 'pinch points' affect the market and what innovative solutions might be deployed in order to improve access.
As already noted, there has been much progress to increase the affordability and availability of childcare. In England all three and four year olds and the 40 per cent most deprived two year olds now get 570 hours of free early education per year (the equivalent of 15 hours per week over 38 weeks of the year). Free early education is largely delivered in day nurseries, pre-schools and the nursery and reception classes in primary schools and rarely through childminders or sessional crèches.
Eligible working parents of three and four year olds will see their allocation of free hours doubled in 2017, to 1,140 hours per year. This ambitious policy is worth £2,545 to parents, based on current prices (Family and Childcare Trust, 2015). However, its implementation presents both opportunities and challenges to providers, which we discuss in the next section of the report on childcare affordability.
The current infrastructure of support also includes help with childcare costs through the childcare element of Working Tax Credit. At present working parents on low incomes can cover up to 70 per cent of their childcare costs through tax credits, receiving up to a maximum of £122.50 per week for one child in childcare and £210 per week for two or more children (i.e. for costs of £175 and £300 respectively). About 8 per cent of the UK's lowest-paid working families benefit from this type of help. From April 2016 parents on Universal Credit began to receive help with up to 85 per cent of costs, up from the previous 70 per cent - although with the same maximum limits of £122.50 and £210.
Parents not in receipt of childcare help through tax credits or Universal Credit can receive support through their employer, including childcare vouchers and the provision of workplace nurseries. An estimated 540,000 UK parents received childcare vouchers in 2013, saving them up to £55 per week if they were basic rate taxpayers (House of Commons Library, 2014). In 2013 the Government announced that it will phase out the present childcare voucher scheme and replace it with the online 'tax-free' childcare scheme in 2017. For each £8 a parent pays in, the Government will add an additional £2 up to a maximum of £2,000 per year per child.
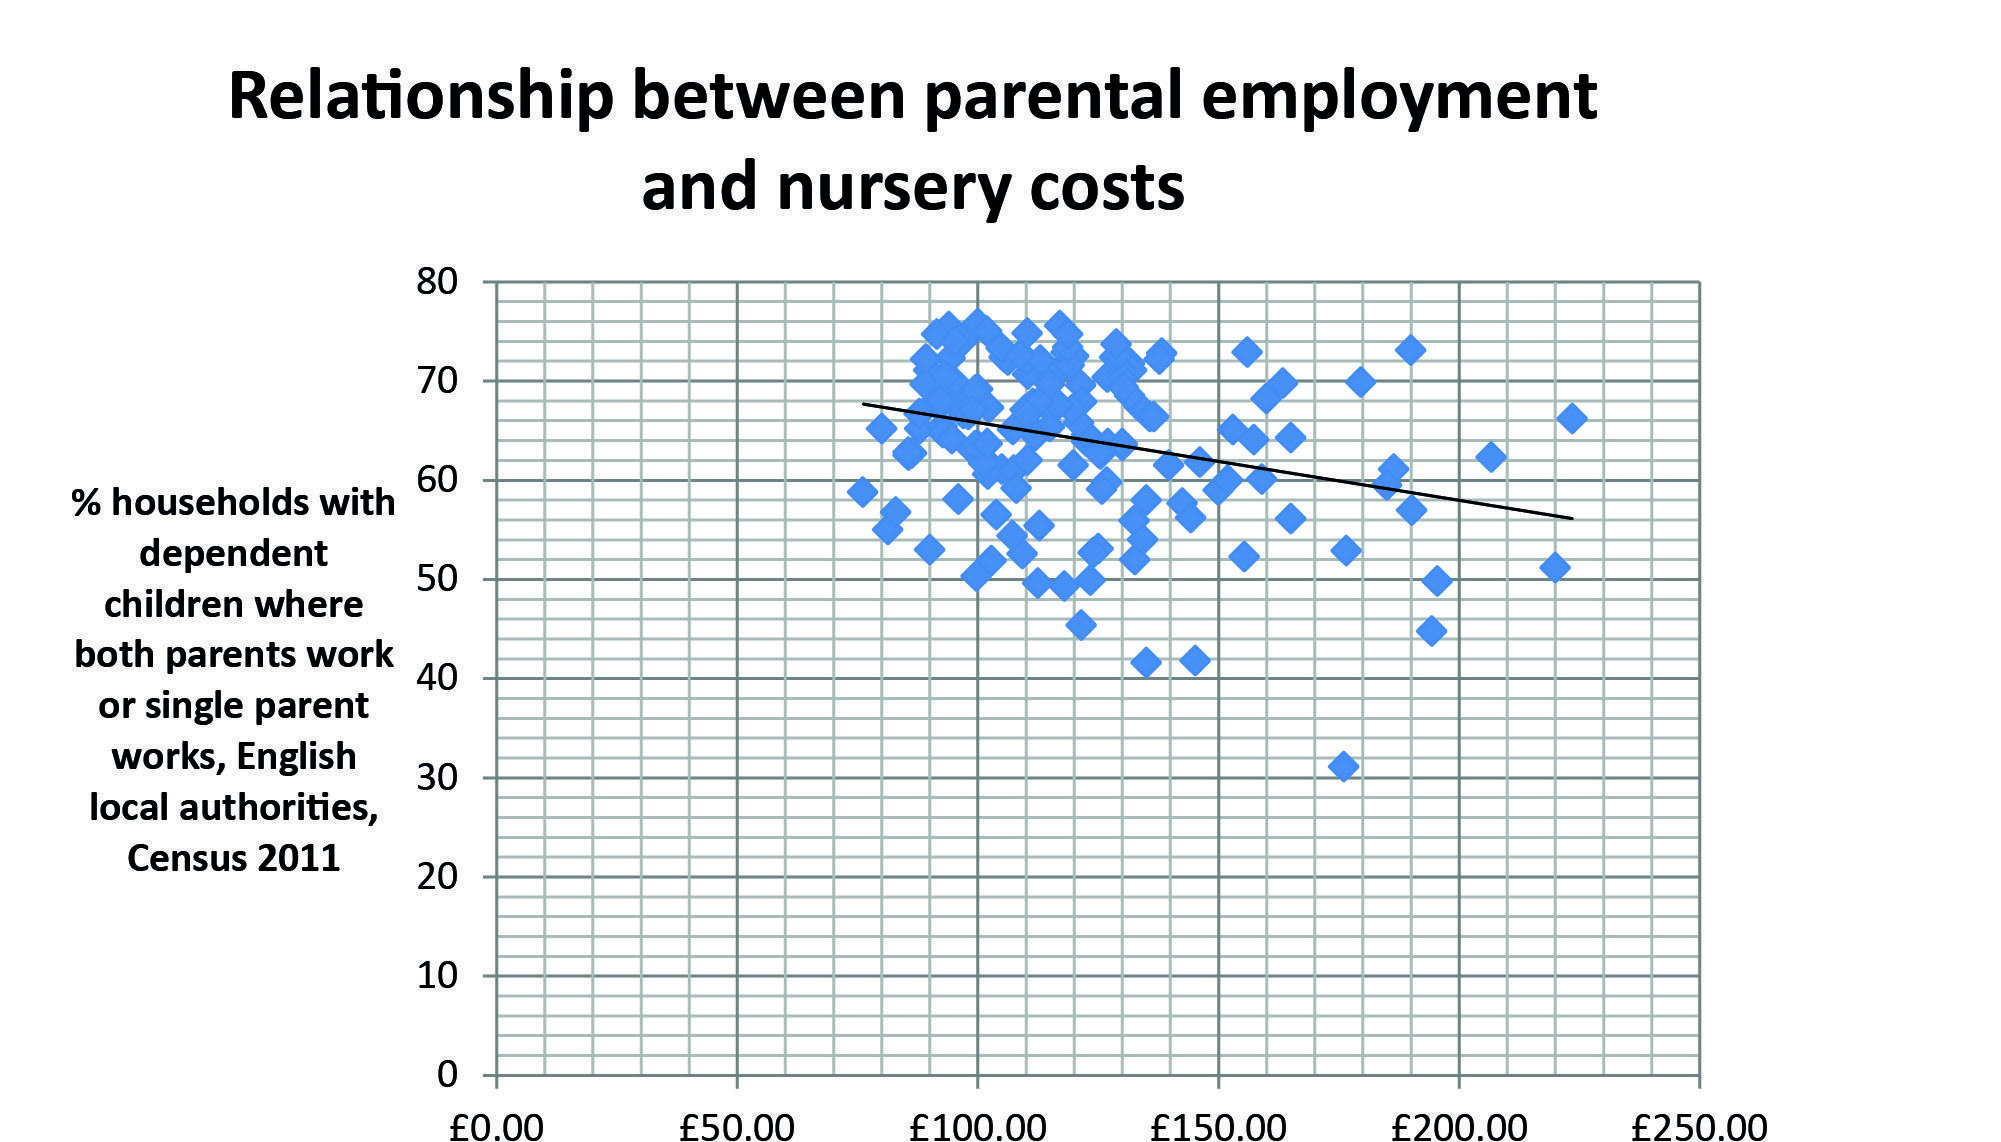
Despite increasing the amount of help with their childcare costs, working parents in the UK pay a higher proportion of their income on childcare than do their peers in many other developed countries. The high price of childcare may act as a barrier to maternal employment and it is significant to note that it is lower in the UK than in many other OECD countries, including Portugal and Poland (Thompson and Ben-Galim, 2014). As Figure 1 shows, there is an association between parental employment and nursery prices. Although causal relationships cannot be drawn from the relationship shown in Figure 1, lower prices are associated with higher parental employment. This suggests that there is potential in many areas to increase the number of families where both parents are working.
Childcare places have also grown over the last 15 years, prompted by:
- The demand-side subsidies (payments to parents) described above.
- Start-up grants and subsidies to cover revenue costs or the expansion of existing provision.
- The requirement placed on local authorities by the Childcare Act 2006 to develop local childcare markets.
CASE STUDY
THE CHILDCARE ACT 2006
The Childcare Act 2006 obliges local authorities in England and Wales to ensure there is sufficient childcare for working parents and those undertaking work-related training. In order to ensure that childcare supply matches demand, local authorities are obliged to carry out an annual childcare sufficiency audit and action plan, to guide their interventions in the local childcare market.
Although there has been an expansion in the overall number of childcare places since the 1990s, this expansion has not been experienced by all types of provider. Places in day nurseries and after-school clubs have increased, whereas there has been a drop in childminder, pre-school and sessional crèche provision. Table 2 sets out the number of places in different types of provision in 2006 and 2013.
TABLE 2:
Numbers of registered childcare places, 2006 and 2013
| 2006 | 2013 | Percentage change 2006-2013 | |
|---|---|---|---|
| Day nurseries | 544,200 | 796,500 | +46% |
| Pre-schools and sessional crèches | 278,300 | 249,900 | -10% |
| Childminders | 272,600 | 226,400 | -17% |
Sources: Childcare and Early Years Providers Surveys, 2006 and 2013
The Childcare Act 2006 also codified private and not-for-profit sector involvement in childcare provision as it only allows local authorities to be the 'provider of last resort'. In consequence, childcare is a regulated mixed-market of private, not-for-profit and public sector provision, with ownership patterns in England set out in Table 3.
As these figures show, the childcare sector is diverse. Today, under-fives childcare can be delivered by childminders working singly or in small groups, part-time pre-school provision, sessional crèches, state nursery schools and classes, single-site day nurseries, small regional nursery chains and national day nursery chains such as Busy Bees or Bright Horizons, both of which run over 200 nurseries.
TABLE 3:
Ownership of childcare provision in England by provider, 2013
| Private | Not-for-Profit | Public - Local Authority | Public - School or College | |
|---|---|---|---|---|
| Nurseries providing full daycare | 61% | 31% | 4% | 5% |
| Sessional early education/ daycare | 39% | 52% | 6% | 5% |
| After-school clubs | 41% | 1% | 4% | 40% |
| Holiday clubs | 60% | 24% | 4% | 12% |
Source: Childcare and Early Years Providers Survey, 2013
There is significant involvement of the not-for-profit sector in childcare provision. This is also a diverse sector which includes registered charities, not-for-profit enterprises and a small cooperative or mutual sector which include about 50 single site parent mutuals as well as Cooperative Childcare, the sixth largest childcare chain in the UK.
The diversity and fragmented nature of childcare provision places is an opportunity for innovation and also a challenge, particularly in relation to business collaboration. We develop these themes later in the report.
SECTION TWO: THE PINCH POINTS
Based on existing literature, data from government and local authority sources as well as the Family and Childcare Trust's own datasets, and our structured engagement with experts and practitioners, we have identified three primary pinch points in the current childcare market: affordability, accessibility and flexibility.
These three pinch points are overlapping categories which together represent the key barriers to access to high-quality childcare. They are therefore also barriers to parents' ability to work and to increasing children's life chances. This report will look at each of them in turn and in detail before proposing pathways for innovation that would help to alleviate these pinch points. But first it is important to illustrate briefly what we mean by each of these factors.
- Affordability: Where childcare cost are high, fewer parents work, and conversely, where childcare is cheaper, more parents work. Affordability is therefore a critical pinch point affecting access to childcare and parental employment.
- Accessibility: The Childcare Act of 2006 requires local authorities in England and Wales to ensure that there is sufficient childcare as far as is practicable - for working parents and those undertaking training or education with the intention of returning to work. However, the Family and Childcare Trust's annual childcare costs dataset shows that, despite an expansion in childcare places, in 2016 only 45 per cent of local authorities in England reported that they had sufficient childcare for parents working full-time. In much of the country, lack of provision also represents a significant pinch point.
- Flexibility: Many parents are employed outside of nine-to-five office hours, or they work hours that can change from week to week. These ‘atypical’ work patterns, including overtime, shift work, weekend working, ‘zero hours’ and on-call working, are particularly common at the lower end of the labour market. Childcare provision tends not to match these new working patterns, creating a third pinch point.
We have identified the three pinch points from the perspective of parents' ability to access high-quality childcare, rather than the quality of the childcare per se. This is because we believe the quality of childcare provision is an overarching factor which must not be compromised, but which is not currently as acute a problem as the pinch points identified above.
All of the innovations and ideas put forward in this report will be able to be implemented without compromising the quality of care which young people receive. Indeed, in some cases the ideas would improve the quality of childcare, for example by diversifying the social mix of childcare settings and providing social capital to young people using the services. All of the recommendations we put forward can be implemented within the current rigorous Ofsted requirements on quality and safeguarding, and will ensure that the fundamental aim of childcare to increase young people's life chances can be met.
SECTION THREE: AFFORDABILITY
Although the amount of help that parents receive with their childcare costs has increased significantly over the last 20 years, high childcare prices still act as a barrier to parental employment. Figure 1 shows that where childcare cost are high, fewer parents work, and conversely, where childcare is cheaper, more parents work.
FIGURE 1:
Relationship between parental employment and nursery costs
Although parents get help with their childcare costs through free early education, Working Tax Credit/Universal Credit and childcare vouchers, certain family types are more likely to be paying a high proportion of their income on childcare:
- Families with children under three who do not receive free early education.
- Families who use full-time nursery care.
- Families whose income is just above the upper limit to receive help through Working Tax Credit or Universal Credit.
- Single parents whose income lies outside the upper limit.
- Families with children under five who live in London or the South East, whose childcare costs may be 25-50 per cent above the national average.
- Families who have no access to informal childcare.
- Families of three or more children.
Table 4 sets out 2016 childcare costs. A family with two children aged two and five using part-time nursery care and an after-school club would typically pay £7,933 per year for childcare.
TABLE 4:
Average weekly childcare prices in England, 2016
| Region/Nation | Nursery 25 hours (under 2) | Nursery 25 hours (2 and over) | Childminder 25 hours (under 2) | Childminder 25 hours (2 and over) | After-school club 15 hours | Childminder after-school pick up |
|---|---|---|---|---|---|---|
| East of England | £113.51 | £110.88 | £104.13 | £104.08 | £51.89 | £63.04 |
| East Midlands | £116.63 | £109.15 | £98.79 | £98.74 | £44.80 | £58.65 |
| London | £158.73 | £148.74 | £148.12 | £146.81 | £54.39 | £88.17 |
| North East | £109.49 | £102.20 | £97.76 | £97.29 | £48.20 | £59.68 |
| North West | £102.44 | £101.08 | £88.67 | £88.21 | £45.80 | £55.95 |
| South East | £137.88 | £133.32 | £117.58 | £116.86 | £50.81 | £71.49 |
| South West | £116.24 | £111.63 | £104.77 | £103.53 | £51.49 | £63.49 |
| West Midlands | £110.80 | £106.91 | £95.43 | £93.06 | £46.92 | £59.64 |
| Yorkshire & Humberside | £97.42 | £93.60 | £92.71 | £91.16 | £45.78 | £55.56 |
| England regional average | £118.13 | £113.06 | £105.33 | £104.42 | £48.90 | £63.96 |
Source: Family and Childcare Trust, 2016
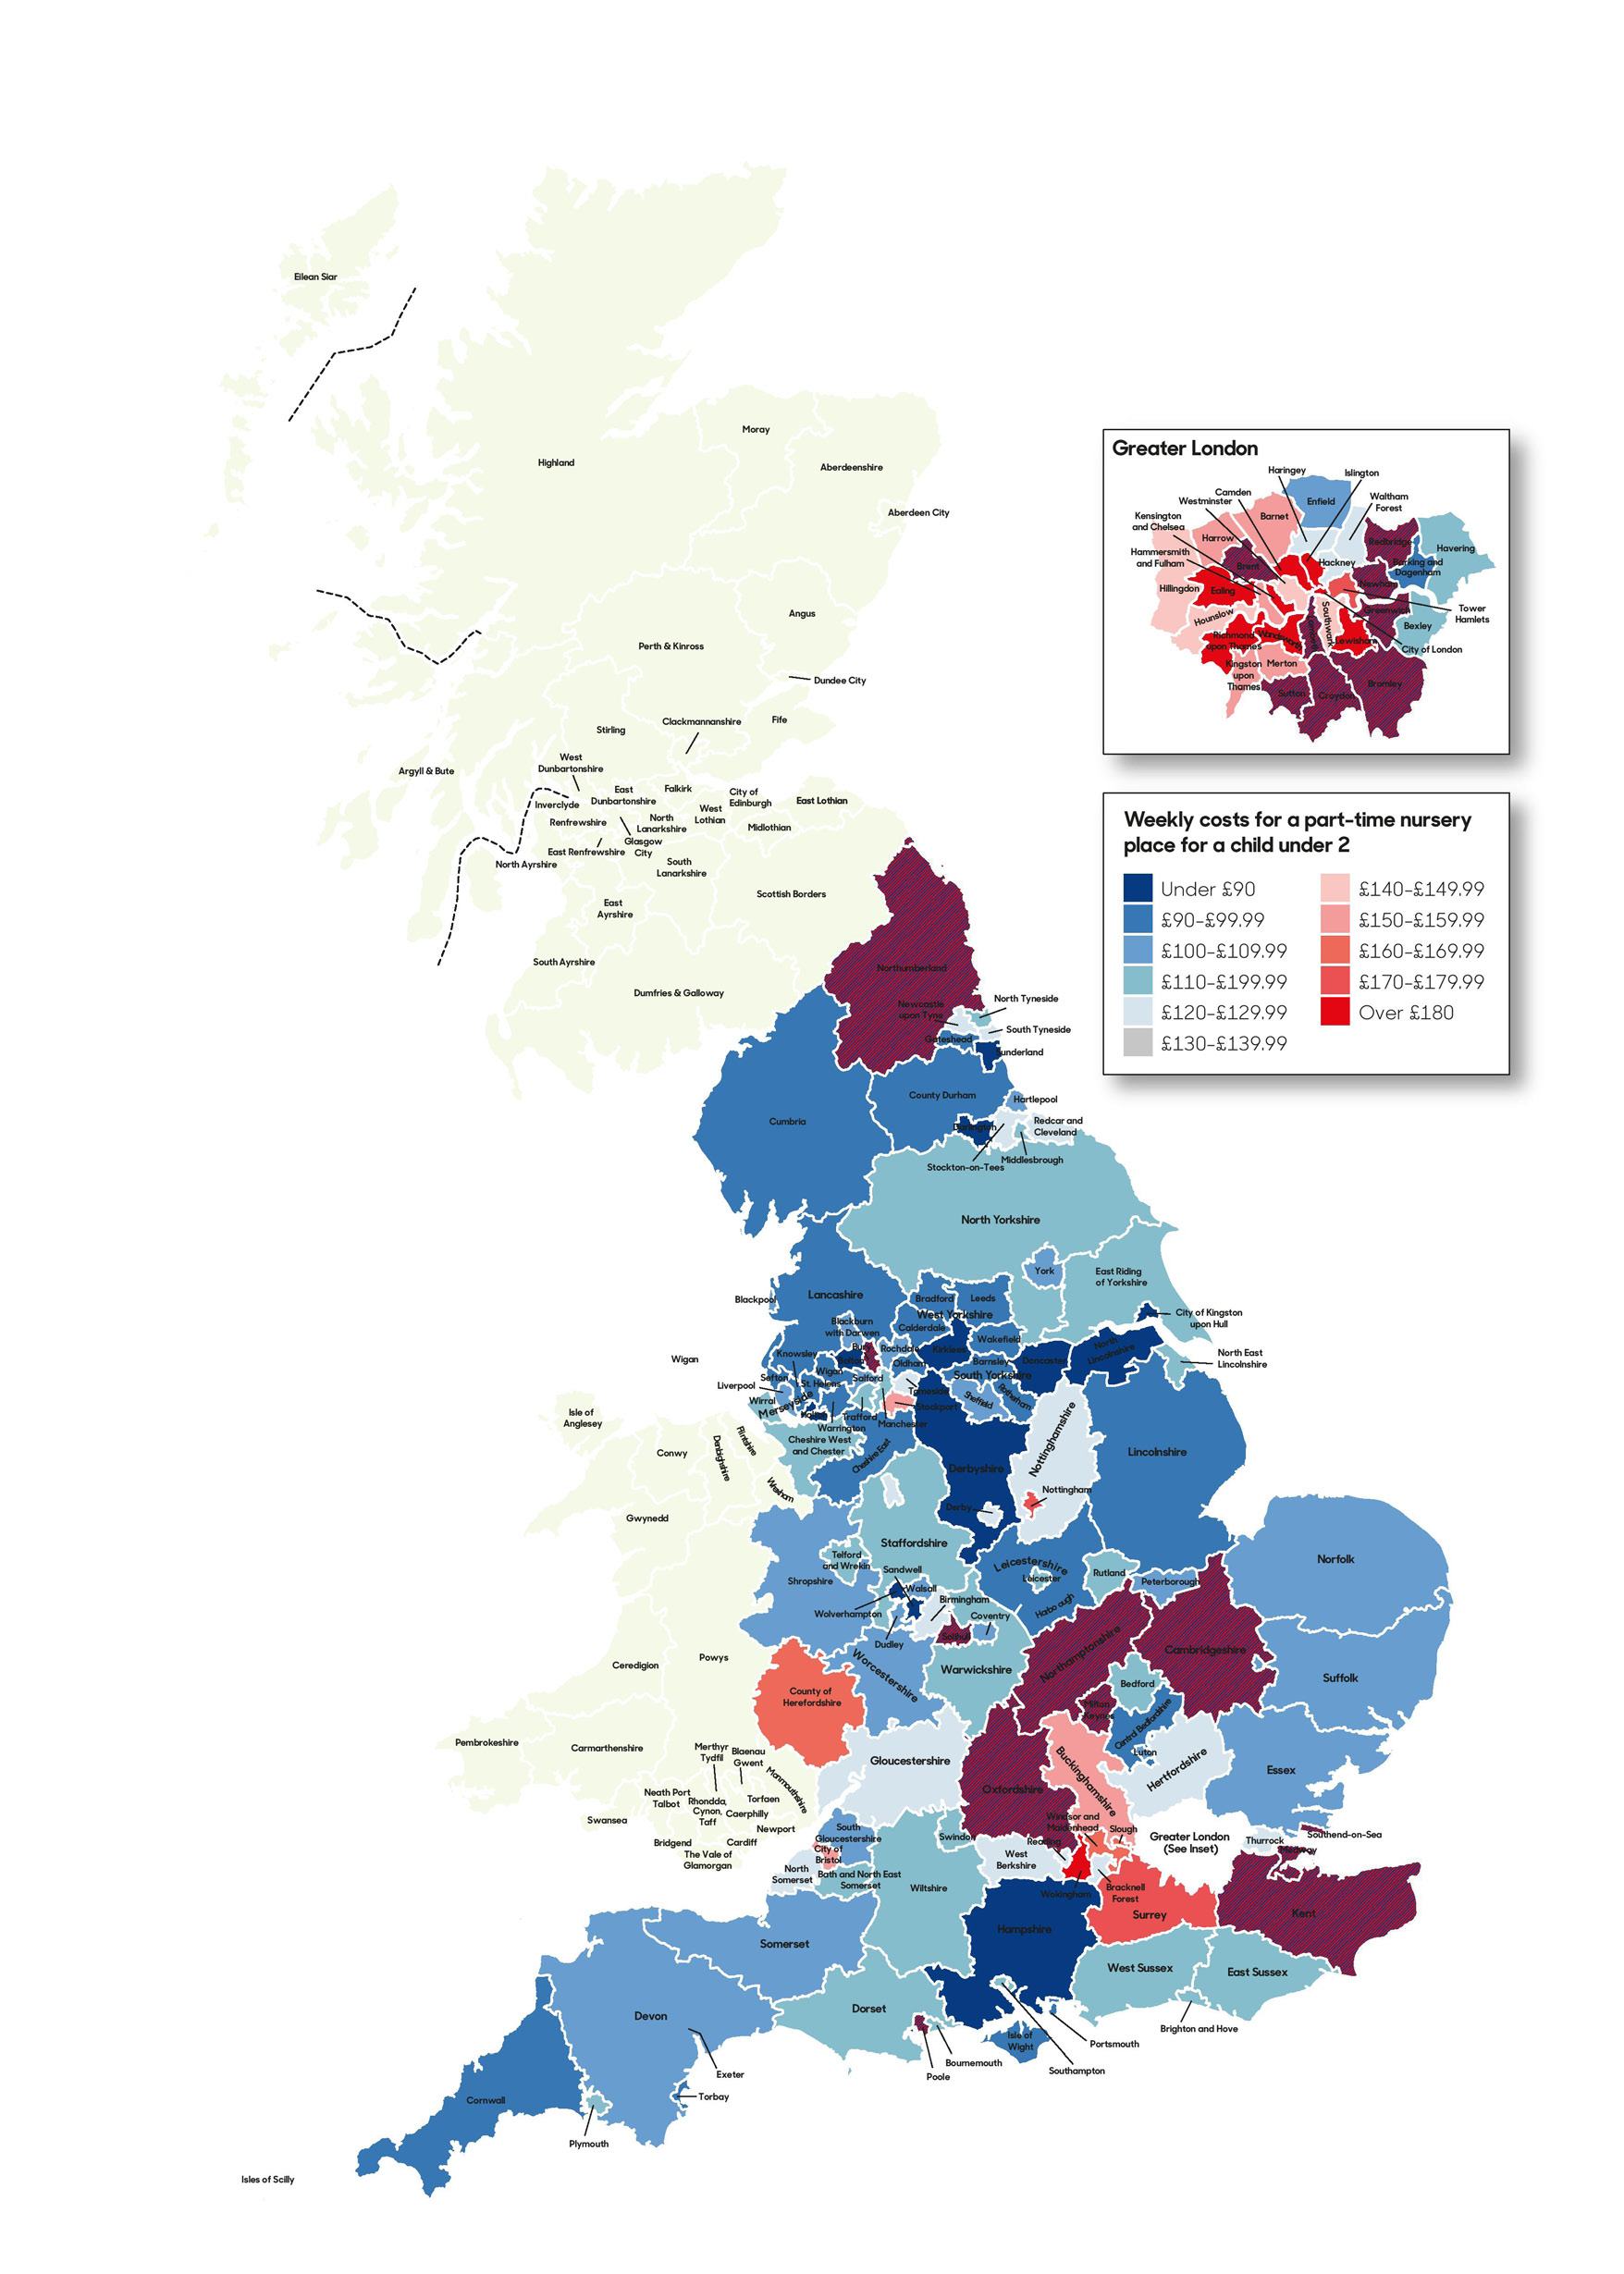
Table 4 also illustrates the regional variations in childcare prices, which can be significant. Within London, a parent in the most expensive local authority would pay £123 more per week, or £6,400 more per year, for a part-time nursery place for an under-two compared with a parent in the cheapest local authority (Family and Childcare Trust, 2015). There are also differences between and within local authorities in the price of childcare, as illustrated in Figure 3. These variations may be a result of:
- Differences in the price of inputs such as staff costs, rent and bank loans.
- Different levels of public subsidy to deliver free early education or subsidised after-school childcare.
- A differential marketing offer to parents, with evidence of a 'luxury' nursery market.
- The nature of provision, with private providers needing to make a profit and the not-for-profit sector needing to make a surplus to cover reinvestment and contingencies.
Figure 2 presents analysis on group-based childcare from the one-off Childcare and Early Years Finances Survey in 2011. Breaking down the costs of delivering childcare, it can be seen that staffing is the biggest component; for part-time nursery provision for a child under two, 77 per cent (£90.32) is staff costs. Costs relating to the building make up the next-largest component, with rent, mortgage, utilities and upkeep of buildings and fixtures together making up 11 per cent of costs.
FIGURE 2:
Breakdown of delivery costs in group-based childcare
A pie chart showing the breakdown of delivery costs in group-based childcare. The largest slice, 77%, is for Staff. Other categories are: Upkeep of Buildings and Fixtures (2%), Other (1%), Utilities (2%), Insurance and Rates (2%), Admin Costs (3%), Material and Food (7%), and Rental and Mortgage (7%).
Sources: Childcare and Early Years Finances Survey, 2011.
Public sector provision is generally less expensive than private and not-for-profit sector provision. In London, for example, in 2015 nursery provision for a child under two was £25.98 per week more expensive in the private and not-for-profit sector than in the public sector (Family and Childcare Trust, 2015). This may be a consequence of lower input costs, for example, use of rent-free premises, or of not needing to make a profit.
Differing levels of public subsidy also cause price variations. Central government gives money to providers to deliver free early education to two, three and four year olds. There are variations in the hourly rate that providers receive, an issue we discuss later in this report. Within the North East, for example, the hourly rate allocated by the Government for three and four year olds in 2014-2015 ranges between £3.49 and £4.67 per hour. Over the course of one year, a nursery getting the higher level of funding will get £673 more to deliver free provision than one receiving the lower level. Where the money nurseries receive from local authorities does not cover costs, nurseries rely on parents purchasing extra hours on top of their existing free provision, and at a higher price, in order to cover costs. This can make childcare expensive and accounts for price variations for nursery provision.
The extension of free early education for three and four year olds to cover 30 hours of childcare (see Table 1) will reduce the opportunities for providers to cross-subsidise free provision by charging parents a higher rate for extra hours. Unless providers can reduce their unit costs, this policy intervention, to be rolled out in 2017, is likely to increase the price to parents of non-funded hours.
Early years providers also operate other cross-subsidies which can cause price variations. The parents of three and four years olds may pay well above costs, in order to cross-subsidise childcare for babies, where higher staffing requirements can make the real costs too high for local families.
FIGURE 3:
Average nursery prices for part-time childcare for a child under two, 2015
Source: Family and Childcare Trust, 2015
INNOVATIONS IN AFFORDABILITY
We have identified a number of innovative solutions that will help make childcare more affordable for families. Working from the evidence, these innovations focus on reducing input costs, for example, using volunteers, deploying staff more effectively or using cheaper premises, and on increasing economies of scale through greater collaboration in order to bring down overall costs to parents.
The Department for Education (DfE) highlighted some of these solutions in a recent review of the unit costs of delivering childcare for the under-fives (DfE, 2015). The review suggests that childcare would be cheaper if there were fewer, but larger, providers and greater sharing of back-office costs, which supports the need for more business collaboration. The review also suggests that childcare could be deployed more effectively, as many providers did not staff their settings up to the maximum staff-to-child ratio set out in the Early Years' Foundation Stage (EYFS) regulations. For example, in private nursery settings the average staff ratio is one member of staff to 3.2 two year old children, rather 1:4 as set out in regulations. However, the ratio of 1:3.2 is based on occupancy rates, rather than the actual number of places available, and few settings operate at full capacity. Our research with providers suggests there is limited scope for deploying staff more efficiently to reduce unit costs, and thus prices charged to parents.
Each of the solutions we set out below speaks to the core pinch point of the cost to families. But the solutions selected also speak to the attitudinal factors that affect parental choices - it is no good reducing the cost barriers to childcare if parents then lose confidence about the quality and safety of that childcare.
CO-PRODUCED CHILDCARE SETTINGS
Staff costs account for 77 per cent of the input costs for childcare providers and therefore represent the biggest single opportunity for innovation to drive down costs.
One way that this can be achieved is by substituting paid staff with volunteers. Such an approach has been implemented in a number of co-produced childcare settings, in the UK and in other, comparable, childcare markets.
There is a long tradition of parents setting up nurseries, pre-schools and after-school provision in the UK: the Busy Bees nursery chain and many pre-schools were set up by parents. In almost every local authority there are after-school clubs which are still run by the parents who set them up, albeit as private or not-for profit organisations. But once established almost all of this provision has been handed over to paid professional staff, although the original parent owners and directors may remain in some cases. Our research shows that there are presently very few nurseries and after-school clubs - fewer than 50 in England - with genuine parental involvement and where parental contributions to staffing helps bring down childcare prices. Most of these settings are run as parent co-operatives, with formal shares and co-operative governance structures. A few are privately-owned or not-for-profit settings, but with formal structures to involve parents as volunteers and workers. Almost all of these parent co-produced childcare settings are located in areas rich in social capital and with significant numbers of adults who volunteer regularly.
The situation in England contrasts with Canada, which has a larger parent co-produced nursery sector, with most of these settings run as co-operatives. In Ontario alone there are over 50 parent nursery co-operatives, supported by the Parent Co-operative Preschool Corporation, a member organisation providing advice. This strong sector has grown over nearly 50 years and has been catalysed by leadership from federal government.
CASE STUDY
GRASSHOPPERS IN THE PARK
This is an example of formalised parental involvement in a nursery parental co-production. The nursery is located in Bethnal Green in London, an area with a comparatively large population of engaged parents. There are three levels of childcare prices dependent on family income, but even for the highest-income group childcare prices are 15 per cent lower than the London average. It was set up by a group of parents and is run by an executive committee of parent directors. Parental involvement is a formalised part of the business model. All parents are expected to offer one or two hours' time contribution every week, for example, helping with administration or childcare. For this, they receive a discount of £40 per month on their childcare fees. Parents taking on more time-consuming roles are required to join the executive committee and receive a further £40 per month discount on their fees. Parents also have the option to work with the children one day a week (a 'parent day') as play-workers alongside trained members of staff, for which they receive a reduction of £120 on fees. This parental involvement has led to some parents, usually mothers, starting new careers in childcare.
In England, the regulatory framework attached to childcare determines the role of parent volunteers. The Early Years Foundation Stage regulations specify minimum staffing ratios for the under-fives (DfE, 2014d). Although there is the perception that parent volunteers cannot be counted in ratios, this is not so. The Early Years Foundation Stage regulations specify:
Students on long-term placements and volunteers (aged 17 or over) and staff working as apprentices in early education (aged 16 or over) may be included in the ratios if the provider is satisfied that they are competent and responsible.
So there is scope for parental volunteering to impact on prices, by:
- Formalising parental volunteering and making it regular so it is counted in staff ratios.
- Bringing down prices by encouraging parental involvement in administration and areas not governed by formal ratios set by the Government.
- Encouraging parental involvement in over-fives provision where ratio requirements are less strict and where the regularity and continuity of parent volunteering is less essential in maintaining quality.
There is also scope to use other (non-parent) volunteers in any or all of these roles. Of course, rigorous processes would need to be put in place to ensure all children are properly safeguarded and that volunteers are appropriately trained and vetted.
More parental and volunteer engagement in the sector also holds out the possibility of helping childcare facilities to overcome some of the challenges presented by recent policy developments. The new National Living Wage has the potential to impact on some providers, particularly outside London (Maughan et al., 2016). Additionally, the government's commitment to 30 hours of free childcare - at a below market rate of payment - will be difficult for providers to fulfil without further reductions in margins. Therefore, bringing more parents and volunteers into the sector could help cushion the childcare market against these challenges.
IMPACT
In the pre-school day sector, there are constraints that are likely to prevent parental co-production from undergoing the radical and rapid growth required to provide large-scale answers to the problem of cost. The stringent regulations on ratios mean that parental involvement would need to be very regularised and formalised, creating a significant barrier to entry - although it may be possible to find ways to overcome this using non-parent volunteers. The outlook for co-production in after-school, breakfast and holiday childcare is much more positive.
We looked at the 'average' after-school club (using data from the DfE's Childcare and Early Years' Providers' Survey (DfE, 2014b)) in order to understand how parent co-production and greater volunteer involvement might work and what impact it could have on costs.
The mean number of paid staff in after-school clubs was 7.2 in 2013, supplemented by 0.7 unpaid staff (DfE, 2014b). The average after-school club has 45.7 registered places and an annual vacancy rate of 20 per cent. Regulations on ratios specify no more than 30 children per paid member of staff, although few clubs have such high child-to-staff ratios.
Family and Childcare Trust data suggest that the average after-school club costs £48.18 per week in 2015. Substituting one paid member of staff with a parent volunteer has the potential to reduce costs by about £5.30 per week or about £200 per year per child. Here, regularity of volunteering may not be as essential in maintaining quality as in an early years setting. Indeed, calling on a larger number of parents with different skills - from battleships to badminton - may be beneficial for children. This points to the opportunities for greater and more flexible parental involvement but it also highlights the huge potential for greater and better use of volunteers in after-school clubs. Not only would wider voluntary participation in after-school clubs mean reductions in cost with little impact on the regulatory status of clubs but it would widen the social capital of children by providing them with opportunities to engage with a more varied range of adults. These benefits would also apply to breakfast and school holiday childcare schemes.
An additional factor that makes parental and volunteer co-production appealing in the over-five sector is the length of time for which parents tend to use these services. Typically, parents use out-of-school childcare for the full seven years of primary education - compared with nurseries, where most children only attend for a maximum of three years. This means that breakfast clubs, after-school clubs and holiday childcare schemes may have a more stable group of parent volunteers than in nurseries, with the latter experiencing volunteer attrition after children turn five.
There is some tradition of using non-parent volunteers in after-school and holiday childcare in Britain. The most recent Childcare and Early Years' Providers' Survey suggests that 5 per cent of staff in after-school clubs are volunteers and 4 per cent are students on placements (DfE, 2014b).
Typically, volunteers are:
- Students in youth, play or childcare courses undertaking placements.
- Gap year students who want an ‘inner city’ experience.
- Those wanting experience prior to starting vocational courses.
- Local artists and musicians who want to offer specific services.
There is potential to expand non-parent volunteering in settings that have few volunteers. Given that schools and local authorities run 44 per cent of after-school provision, local authorities or groups of schools could recruit and support non-parent volunteers.
Through the Centre for Social Action Innovation Fund, Nesta and the Cabinet Office have invested over £12 million to support a range of innovative approaches to volunteering to tackle social problems and develop 'people-powered' services. On the back of this experience, Nesta has begun working with schools to explore the potential for them to develop more structured and effective ways of working with volunteers, of the kinds that are well-established in, for example, hospitals or museums.
Our conclusion, therefore, is that there are significant opportunities for parental co-production and volunteering to reduce costs in breakfast, after-school and holiday childcare settings. Such an expansion would also overcome another pinch-point in childcare provision, that of long-standing shortages of out-of-school childcare, with 28 English local authorities (18 per cent of the total) reporting shortages of holiday childcare in 2015 and 38 (25 per cent) reporting shortages of after-school care (Butler and Rutter, 2015).
BARRIERS TO ADOPTION
Examining the experience of parent co-produced nurseries in Canada points to some of the barriers to adoption which might restrict the expansion of this kind of "people-powered childcare" in England, which include:
- No local founder-initiator to start the venture.
- Not enough committed parents in a given locality to devote time to volunteering.
- Lack of parents with the skills, experience or confidence in their ability to be involved in running out-of-school childcare.
- Time constraints on parents who may be working full-time or find it difficult to devote sufficient, regular time to the childcare setting.
- Lack of suitable premises.
- Planning regulations.
- Start-up costs and difficulties breaking even as a new business.
- Instability caused by the high turnover of parent users.
- Lack of infrastructure for recruiting and placing non-parent volunteers.
- "Leave it to the professionals" - negative attitudes from local authorities, schools and early years professionals towards parental involvement in childcare.
Out-of-school childcare specifically has a low priority within local authorities and central government, so there is relatively little incentive to innovate and few penalties for not providing sufficient childcare.
NEXT STEPS
Many of the above barriers could be overcome if there was leadership from a support organisation, who could help parents find premises, negotiate planning regulations and handle Ofsted registration. A support organisation could also assist in recruiting non-parent volunteers. In Canada, the Parent Co-operative Preschool Corporation has acted as a focal point, bringing interested parents together and providing them with advice and business support, including advice on raising capital. There is no equivalent organisation in England, although the New Schools Network has supported groups who want to set up free schools and is a potential model of how a childcare support organisation might work.
CASE STUDY
THE NEW SCHOOLS NETWORK
Based in central London, this charity was set up in 2009 by a former special adviser to Michael Gove, the then-Secretary of State for Education. It aims to help groups who want to set up free schools. Currently employing 15 staff, it assigns a dedicated adviser to bidding groups, as well as providing specialist advice on, for example, human resources or curriculum. The organisation gives feedback on bids to the DfE, as well as running events for those in the earlier stages of the process. The New Schools Network receives grant funding from the DfE and a range of other donors.
It's worth noting that the New Schools Network focuses on the bidding process and does not provide ongoing mentoring service for new free schools, which often face problems in the early years of operation.
PROVIDER COLLABORATION
One of the recent changes on the nursery market has been the growth of smaller 'regional' chains of five to ten nurseries, which operate alongside single-site nurseries and larger, national nursery chains such as Busy Bees or Bright Horizons. One of the financial advantages of regional chains is that settings are close to each other and they can easily share running costs, particularly bank staff, payroll and administrative costs and the bulk ordering of food and materials. As settings are located near each other, bank staff can be deployed across a number of settings.
There are also a growing number of multi-service childcare providers. Here a private or not-for-profit organisation may provide nursery care alongside other childcare services such as after-school, holiday or out-of-hours care. Staff are deployed across all of the services and there are other economies of scale.
The success of regional nursery chains and multi-service childcare providers points to the potential for local business collaboration. Most childcare providers are small and operate from a single site. Groups of childcare providers could share some of their operating costs such as agency staff or administrative costs. This could mean day nurseries pooling their administrative and back-office costs in order to reduce staffing costs to individual businesses or more co-location at appropriate premises between daycare facilities and after-school and holiday clubs. In either instance, the opportunities to reduce input costs are significant - meaning real savings for parents and families. This model for innovation also has a potential beneficial impact on quality; pooling back-office or location costs should enable small enterprises to improve their purchasing power and therefore the overall standard of both staffing and facilities.
There have been attempts to promote greater local business collaboration in the past, through the Early Years Development and Childcare Partnerships (EYDCPs) which ran between 1999 and 2004 in England, with similar initiatives in Scotland and Wales. These led to some genuine and long-lasting collaboration, for example, out-of-school clubs using children's centre premises and sharing other fixed costs. But the EYDCPs were funded by central government and run by local authorities and when funding ended, most attempts at business collaboration ceased.
Childminder hubs or networks are a further example of provider collaboration. Under half of local authorities now fund and run childminder hubs or networks. But the extension of free early education to cover 30 hours per week (1,140 hours per year) for the working parents of three and four year olds offers an opportunity to extend this type of collaboration. This policy change will be implemented in September 2017 and will require additional early education places, as many parents will increase their hours of childcare use. While new provision will be set up and some existing providers will be able to expand to meet increased demand, the capacity for expansion in London and other densely populated urban areas is limited by shortages of physical space. Here, parents may have to take their allocation of free hours from two providers, for example, 15 hours from a school nursery or children's centre nursery and 15 hours from a childminder. This will necessitate a number of childminders working around a school, taking one group of children from nursery at noon, while picking up another group to take back to their home for their care. As well as helping in the implementation of the 30 hour extension, childminder hubs might also lead to greater business collaboration between providers and sharing back-office costs.
CASE STUDY
PERSONAL TESTIMONY FROM SARAH FORSTER, MEMBER OF YORK CHILDMINDING HUB
We have a very strong childminding partnership in our area that has progressed and been enhanced by the [funding] support of New Earswick Children's Centre, where we are provided with a weekly session where we can meet, plan activities and carry them out and offer support to each other. This has recently progressed with the start of the Hub pilot scheme. The benefits of the Hub to us as a group and as individuals are huge. As lone workers it can feel very isolating at times, as we are left to decipher the EYFS, work with parents and often learning as we go along. The Hub means we have professional support where we can ask advice and be included in training and enhancing the childcare provision in our area. Historically childminders have not always been seen as professional childcare practitioners and working with the Partnership and the Hub is a way in which we can change these antiquated views and is helping us to feel more confident in our practice as the professionals that we are. The Hub is an opportunity for us all to share our expertise and improve standards.
IMPACT
About 11 per cent of the costs of providing group-based childcare are related to buildings: rent and mortgage costs, building maintenance and utilities. There is some scope to share premises - for example, a pre-school that shuts at 3pm could share premises with an after-school club. We think that greater business collaboration has the potential to save 3-5 per cent of running costs through economies of scale, and where bank staff are used more efficiently. In the 'average' nursery previously described, with running costs of £86,000 per year, business collaboration has the potential to reduce costs by about £2,500 per year, or about £50 per child. This will make little difference to nursery prices charged to parents, but it may have a more significant impact on margins. Thus the justification in supporting business collaboration might be to overcome another problem of the childcare market - challenges to business sustainability and thus shortages of provision in deprived areas.
BARRIERS TO ADOPTION
There remain significant barriers to the adoption of better collaborative working between providers, including;
- Competition between childcare providers with neighbouring businesses seen as rivals.
- A lack of suitable premises that may lend themselves to being used for different groups of children requiring childcare.
- A lack of examples and guidance from central government on opportunities for business collaboration.
NEXT STEPS
In the long-term, there may be a trend towards more regional mergers and acquisitions in the nursery market and larger numbers of multi-service childcare operations. But evidence to date suggests that these developments are largely restricted to the most prosperous parts of England. There is a clear need for more childcare business collaboration in deprived areas. If this is to happen it is likely that leadership and catalysis from central and local government will be needed to promote it, in the form of guidance, examples of good practice and funding for pilot projects. One exciting way to promote better collaboration would be in the form of a 'challenge prize' to incentivise better innovation - giving local authorities and providers themselves both support in developing collaborative childcare and rewards for success.
CONCLUSIONS ON AFFORDABILITY
It is clear that there are major opportunities for innovations to bring down costs to providers and therefore to parents and families. Bringing more parents and volunteers into childcare provision holds significant potential. Staffing costs represent 77 per cent of overall input costs in the average childcare setting. In areas of strong social capital there may be opportunities to use volunteers to bring down the cost of daycare, but regulations on ratios limit the likely impact of such interventions on the majority of families. In after-school, holiday and breakfast club settings, however, there is huge potential. The cost per child could be reduced by around £200 per year - and innovations of this kind bring with them additional benefits in terms of the social mix and potential social capital available to young people who use these services.
Even without bringing large numbers of parents or external volunteers into the mix, there are opportunities for childcare providers to reduce their input costs. Sharing locations - for example between daycare facilities and pre- and after- school clubs - could significantly reduce input costs for providers. It also holds the potential to improve the quality of available facilities because pooled resources will improve the buying power of providers. One unexplored area for potential innovation would be to share premises with other kinds of service - from adult care to libraries.
Other opportunities for better collaboration include shared back-office costs - reducing the cost to providers of crucial activities such as accountancy, agency staffing and janitorial services. Childcare providers have the opportunity to push down costs for themselves and for parents in this way - but it requires leadership and support.
Both successful collaboration and better co-operative and collaborative solutions will need encouragement, seed funding and expert support. Supporting innovation in this area should be a priority for both central and local government.
SECTION FOUR: ACCESSIBILITY
As already noted, the Childcare Act 2006 obliges local authorities in England and Wales to ensure that there is sufficient childcare as far as is practicable - for working parents and those undertaking training or education with the intention of returning to work. In order to ensure they have sufficient childcare, local authorities need to know about any gaps they might have by undertaking annual childcare sufficiency audits. We have used the data in these annual audits to map current gaps in provision, which we set out in Figure 4. The analysis we present is supported by the Family and Childcare Trust's annual childcare costs dataset. Despite the expansion in childcare places, this dataset showed that in 2015 just 43 per cent of local authorities in England reported that they had sufficient childcare for working parents.
FIGURE 4:
Local authorities with sufficient childcare for parents working full time, 2016
It is clear that the uneven distribution of provision represents a major barrier to accessing childcare in certain parts of the country. Our mapping of childcare provision highlights these spatial gaps. The largest gaps are in free early education places, after-school and holiday childcare (Butler and Rutter, 2015). These gaps in provision are almost always most acute in deprived areas. For example, in Hartlepool a deprived local authority - there are just 33 registered places per 100 children, compared with 57 places in Wokingham. Working parents in deprived areas may face higher prices, much less choice and real shortages.
These shortages have come about because most childcare in the UK is delivered by private and not-for-profit organisations who need to break even or make a surplus. The childcare market is, rightly, bound by rules to determine its quality, which set a fixed minimum cost for providers. Most childcare providers operate on low margins that are highly sensitive to small changes in income or outgoings.
In deprived areas parents are less able to pay for childcare, or purchase extra hours on top of their allocation of free early education. Existing providers, in turn, may find it harder to break even or expand provision and new providers may be deterred from entering the market. The non-profit London Early Years Foundation has developed a business model where fees from settings in wealthier areas and better-off parents cross-subsidise costs for other settings/parents. However, this model relies on the kind of population mix/density that is probably only found in a few major cities. It is significant to note that many of the large national chains have little or no presence in the less prosperous parts of the UK.
Even in less deprived areas, there might be near market saturation for mainstream childcare, but gaps remain for particular types of need - for example, childcare for disabled children or in sparsely-populated rural areas.
There are several reasons for these gaps, including:
- The high costs of entry into the nursery market, particularly where rents are high and suitable premises scarce.
- Difficult lending conditions, especially to small businesses, and concerns about the wider economic climate.
- Uncertainty about parental demand.
- Low profit margins and difficulty breaking even, most acutely in deprived areas.
The DfE has recently launched a Childcare Investment Readiness Fund, which aims to leverage more investment into the sector. However, these market barriers and risks also act to deter potential investors, as well as childcare entrepreneurs and innovators. In our research we have come across a number of social investors who are extremely keen to invest in childcare provision, but to date there have been very few deals.
INNOVATIONS IN ACCESSIBILITY
ALTERNATIVE MODELS OF FINANCING
As outlined in previous sections, co-production and collaboration between providers can help reduce costs, and there are some promising ideas to build stronger systems for reciprocal and informal care within communities where formal provision is limited. There may also be greater opportunities for non-profit providers to cross-subsidise, although, as discussed in Section Three, the expansion of the 'free childcare' offer to 30 hours will constrain this.
As we have seen, the UK has a complex public-private childcare market, with diverse, primarily small-scale providers, and mixed funding, with government subsidies to both parents and providers, alongside fees paid by parents. It is clear that this system is not currently delivering sufficient childcare across the country, and that there are particular issues around provision for disadvantaged families and children.
Ultimately, creating enough places to meet the scale of the childcare gap - whether through growing existing provision, or developing new models of care will require new forms of financing. This is especially true for families in deprived areas where the gap is largest and the market barriers most severe.
These forms of funding need to create the space to create and establish new services, and build more sustainable funding streams from the outset. There are valuable lessons from earlier attempts to expand childcare provision, such as the Neighbourhood Nursery Initiative.
CASE STUDY
THE NEIGHBOURHOOD NURSERY INITIATIVE
The Neighbourhood Nursery Initiative ran between 1998 and 2004, providing grant funding to set up 1,400 nurseries offering 45,000 early education places in deprived areas (Smith et al., 2007). It provided capital investment of almost £128 million as well as revenue funding of almost £240 million to subsidise running costs for three years on a tapering basis. These nurseries were run by private (40 per cent of providers), not-for-profit (23 per cent of providers) and public provision (20 per cent of providers). Some 17 per cent of provision was run jointly and collaboratively between the public sector and other providers a type of ownership structure that is no longer in place. It is worth reflecting on the arrangements for jointly-owned nurseries, as they offer examples of innovative collaboration. Some jointly-owned nurseries were run by private and not-for-profit organisations, but based on sites owned by the public sector, usually schools or children's centres. Other sites had staff from public sector and other providers working together. A key lesson from the Neighbourhood Nursery Initiative was the difficulties providers faced in stimulating demand and breaking even in deprived areas. These financial challenges acted as a brake on much innovation by the new nurseries.
MIXED FUNDING
The need to provide a safe, developmental and nurturing environment for children rightly imposes a relatively high cost of entry on new childcare businesses. Combined with relatively low margins, this means that these businesses are not attractive for commercial credit or social investment. On the other hand, the experience of the Neighbourhood Nurseries Initiative demonstrates that simply tapering grant funding over a period of time and hoping that new income streams will emerge to fill this gap is not enough in itself.
Nesta has recently launched the Arts Impact Fund, a 'blended fund' which combines fully commercial lending, grant funding from the Arts Council, and a middle tier of loans with a higher risk appetite (i.e. prepared to back ventures which are less likely to repay in full) and more 'patience' (i.e. prepared to wait longer for a return). It is an investment fund, seeking to back ventures which can become financially viable and provide a return. Arts ventures offering high social and artistic 'return', but which are less proven, or need longer to get onto a sustainable footing, can access different kinds of start-up capital alongside the commercial loan. By combining these different kinds of finance in one investment deal, we ensure that we focus on long-term sustainability from the beginning.
A childcare investment fund that took this kind of innovative approach to funding expansion and development of new childcare businesses would be a hugely valuable addition to the current funding landscape. The DfE, or other parts of government, could play the same role as the Arts Council, providing the bottom tier of funding which is least likely to be returned. This money underwrites the fund, attracting commercial or social investors who currently struggle to lend to childcare businesses. By being an active party in the fund, the government would also be able to direct investment towards solutions for families and areas which are currently underserved.
PROVIDER FUNDING
The UK's mixed market for childcare is not the only model. A number of other OECD countries, such as France and the Scandinavian states, pay for childcare primarily through direct government funding for providers. This model does not have to be more expensive - France spends less on childcare as a proportion of GDP than the UK – and levels of parental satisfaction and maternal employment are relatively high. Indeed, from first principles, demand-side subsidies (such as funding via parents) enable customers to pay more, and will therefore tend to lead to higher prices. There has been some movement in this direction recently, with the expansion of the free childcare offer and the DfE consultation on costs.
Putting a provider-funding model into practice would mean unwinding the existing mixed market, and this would not be straightforward. For example, it seems likely that funding this approach would mean redirecting tax credit/Universal Credit payments that would have gone to families into a separate fund, which could then be used to pay providers. However, there may be scope to pilot a new approach in a specific underserved location.
We suggest that the DfE, the Department for Work and Pensions (DWP) and the relevant local authority/ies jointly establish an initiative to test direct funding to providers operating in underserved areas. They would need to work together with providers, social and commercial investors and an organisation such as the Family and Childcare Trust with expertise in childcare markets to design and trial the system. Providers who delivered to areas and/or families matching the agreed criteria would then be funded fully from the money set aside for the scheme between the partner agencies. The impact on access to childcare, children's attainment and parental employment would need to be rigorously evaluated using control data from other comparable communities. Potential choices for such a trial would have a high level of unmet childcare need, low levels of parental employment, and a high degree of local devolution to enable effective implementation and the realisation of savings across education, welfare and benefits on a 'total place' basis.
OUTCOME-BASED FUNDING
Commissioning of adult care services increasingly seeks to focus on 'outcomes' - the results for service users rather than the delivery of activities. This is not a feature of the current UK childcare market, not least because there are many 'buyers' (parents, employers and the state), and many different funding streams. However, we know that access to good quality childcare delivers two highly important sets of outcomes, especially for low-income families - better early development, educational attainment and life chances for children; and better access to work for parents.
Given the importance of these outcomes, it does seem that it would be useful to experiment with models that can channel funding to childcare providers on the basis of the results they achieve. Two ideas seem promising:
- An upfront quality/disadvantage premium, which would pay providers extra money for delivering good quality childcare to disadvantaged children. This could be paid per child, drawing on the model of the pupil premium, which has channeled resources towards schools serving lower-income communities. It would need to include a strong focus on quality, to ensure that providers were contributing to good outcomes for children. This kind of predictable, upfront subsidy would incentivise childcare provision in underserved communities, and should also help these childcare businesses access credit.
- An alternative would be to pay providers a bonus on achieving specified outcomes. In theory, these could be related to disadvantaged children's school readiness ensuring that they do not start school with a significant attainment gap - although this would pose measurement challenges, and would not be paid until after children had left the childcare setting. It might be simpler to link payments to parental employment, which is likely to happen sooner, is relatively simple for DWP and HMRC to monitor, and represents a direct saving to the government so is relatively easy to monetise. In an ideal world, bonus payments would be linked to both outcomes, in order to incentivise both quality and accessibility to low-income parents.
The detailed policy and fiscal rationale and operational mechanisms for either of these ideas would require significant further thinking and development. While there is clear potential for data-driven approaches to deliver highly targeted subsidies, there is currently limited data on children before they go to school. As with provider funding, it would make sense to trial any new approaches in specific underserved places.
IMPACT
There are significant spatial gaps in the provision of childcare in the UK and these gaps are concentrated in the most deprived areas. It is difficult to see what incentives currently exist to galvanise private sector responses given high start-up costs and the high risk of entry. The fact that the childcare market is dominated by small businesses with tight margins makes it unattractive to investors - especially when serving more disadvantaged communities. There is the need for a new infrastructure of investment and incentives that align the interests of providers and investors with those of government in improving access.
The three ideas outlined above a blended investment fund for childcare, a trial of direct funding for providers, and experimentation with outcome-based subsidies - all have the potential to create sustained new sources of funding for childcare provision in underserved areas.
A new investment fund, underwritten by the DfE, would leverage social and commercial investment finance into the sector, and offer childcare providers a cushion of more patient funding that would enable them to establish their business model over time and access additional commercial credit - while also ensuring the discipline of a sharp focus on financial viability over the long term.
The advantage for providers of direct funding is clear a predictable income stream that smooths out fluctuations in demand, and helps them bear the risk of entry into less prosperous communities. While not directly leveraging in new sources of finance, it seems likely that this model would make it easier for individual providers to access bank loans or other forms of credit. A childcare premium for providers in disadvantaged communities would have the same impact. Payment on outcomes, while not helping directly with the cost of entry, would represent a new future income stream which providers might be able to borrow against.
BARRIERS TO ADOPTION
There are significant hurdles to deploying any of these new mechanisms to catalyse and galvanise expansion of childcare, particularly in deprived areas. These include:
- Lack of common childcare policy agenda between government departments leading to a lack of clarity on the cost-benefit and potential long-term savings from further investment, and a lack of collaboration on innovative funding models/subsidies.
- Complexity of the current market and funding landscape, making it difficult to unwind existing models and start again, and meaning there is no 'single buyer' who can commission new solutions.
- Small-scale nature of most provision, leading to concerns about long-term financial viability and high transaction costs for any investment deals.
- Weak track record of expansion into and sustainability within disadvantaged areas tending to discourage both providers and investors.
- Lack of data on coverage and quality of pre-school childcare provision, making it hard to build an evidence base or target subsidies smartly.
NEXT STEPS
There is no doubt that the barriers to developing a new funding and incentive infrastructure for the childcare market are extensive. However, the failure of the current market to reach disadvantaged areas or respond to demand is also clear. New solutions are needed. As a first step, more research is needed into the potential of the ideas outlined here, and the extent to which they might affect the incentives for providers and investors alike.
Where any of these ideas appear to have potential, we recommend investing in trials to test and demonstrate the concepts in practice. This could include an investment fund targeted at disadvantaged areas, the development and establishment of new models of care, and/or at expansion of childcare very broadly. It could also include a place-based trial exploring one or more of the ideas above around provider and/or outcome-based funding. There is also a need for stronger collaboration between the DfE, DWP, HMRC and Treasury on the economic and social rationale and value of childcare.
CONCLUSIONS ON ACCESSIBILITY
Access to appropriate childcare in the UK is patchy, with those who live in economically and socially deprived areas most under-served. This is a multifaceted problem with consequences for a wide range of government policy objectives. Inadequate childcare access leads to fewer parents working and worse outcomes for children.
Part of the answer lies in improving the number of good-quality childcare places available in deprived areas. It is difficult to see how the free market alone will respond to this need - it certainly hasn't as yet. But there may be opportunities for innovative financing mechanisms to tackle this problem. There are many barriers to this but they are not insurmountable and government should explore the feasibility of new forms of investment and funding for new or augmented childcare facilities.
SECTION FIVE: FLEXIBILITY
There are - as discussed so far in this report - significant problems with the affordability and accessibility of childcare. Crucial to the modern economy is the flexibility of vital services - and here, too, childcare provision falls short. There are significant 'chronological' gaps in availability which create a real pinch point around flexibility - meaning that, too often, care is simply not available when parents need it. The major flexibility gaps are:
- Shortages of childcare in the school holidays.
- Shortages of childcare for parents with atypical work patterns.
HOLIDAY CHILDCARE
While holiday childcare provision has increased, this type of childcare remains in short supply (Family and Childcare Trust, 2014). There are some specific problems in filling gaps that are unique to holiday childcare. First, families tend to use just one or two weeks of provision, so providers are faced with an uncertain market. Second, there is no agreed 'offer' and a great deal of segmentation in the holiday childcare market, with 'luxury' clubs offering a range of exciting activities alongside more basic provision that is often based in schools.
FILLING THE GAPS WHERE PARENTS
HAVE ATYPICAL WORK PATTERNS
Many parents are employed outside of normal nine to five office hours, or have jobs where the hours they work can change from week-to-week. These 'atypical' work patterns include overtime, shift work, weekend working, zero hours and on-call working. Data from the Labour Force Survey suggests an estimated 35 per cent of those in employment work overtime hours. The use of zero hours contracts has grown to include about 800,000 workers. The self-employed may also experience irregular patterns of work, with over 15 per cent of the workforce being self-employed in 2015.
Both employment outside normal office hours and irregular patterns of work can make arranging formal childcare very difficult. As a consequence, many parents with atypical work patterns share childcare with their partners a strategy sometimes termed shift parenting. Others rely on informal childcare, with grandparents most likely to provide this type of childcare (Rutter and Evans, 2012). However, not all parents are able to turn to partners, relatives and friends to provide childcare and those that can't access other formal or informal childcare may face severe constraints in finding work. This is one reason that the government now requires that local authorities include parents with atypical work patterns in their annual childcare sufficiency audits (DfE, 2014c).
DEPENDENCE ON INFORMAL CHILDCARE
The increased use of informal childcare has the potential to solve two childcare problems. First, informal childcare has the potential to fill the gap in childcare that is available outside normal office hours or needed at irregular intervals.
Second, parents' childcare costs might be reduced by substituting some paid-for formal care with informal childcare. This happens already, with 35 per cent of parents with children under two regularly using informal childcare in England (DfE, 2014). Most informal care is provided for free by close family members, particularly by grandparents. The expansion of formal childcare in England has not resulted in fewer families using grandparent childcare. Rather, families tend to use this care less frequently, or in combination with formal childcare.
Informal childcare is less frequently provided by friends and neighbours, with 6 per cent of parents using informal care from this group in the 2013 Childcare and Early Years Survey of Parents. Where friends and neighbours are used, it is usually on a 'one-off' or emergency basis (Rutter and Evans, 2012). Importantly, the 2009 Childcare and Early Years Survey of Parents shows that 66 per cent of friends and neighbours received payment in kind for informal childcare, most usually reciprocal childcare: 49 per cent of parents who used friends and neighbours provided reciprocal childcare themselves.
Rutter and Evans (2012) examined reciprocal childcare provision among friends in greater detail, looking at practices such as babysitting circles which were often set up through local National Childbirth Trust groups or mothers who met at children's centres. They concluded that reciprocal childcare between friends and neighbours was largely restricted to emergencies and out-of-hours babysitting and rarely used regularly during the day. Some of these babysitting circles used alternative currencies in the form of tokens, as a way of regulating inputs and ensuring fairness within the babysitting group. The research argues that the requirement to register some of these arrangements with Ofsted and some well-publicised cases of parents being investigated for non-registration had acted to discourage reciprocal childcare. (Regulations on parents providing reciprocal childcare now allow them to provide up to three hours care every day without registering with Ofsted.) They also found that reciprocal informal childcare was strongly associated with parental social grade, with such arrangements very rare among social grades D and E. This may be a result of more limited social networks and social capital in deprived neighbourhoods.
FORMAL CHILDCARE FOR PARENTS
WITH ATYPICAL WORK PATTERNS
There are places where formal childcare provision meets the needs of parents with atypical work patterns. This flexible provision includes:
- Childminders, as they are more flexible to changes in hours, and can sometimes offer early, late, overnight or weekend care.
- Nurseries, breakfast clubs and holiday childcare that is open by 7.30am and stays open until 7pm where there is demand.
- Workplace nurseries in places that employ a large number of staff who work outside normal office hours, for example, hospitals and airports.
- Sessional crèche provision for parents with irregular work patterns.
- Childcare provided in a child's home by registered carers, with arrangements brokered by employers, local authorities, digitally or by private businesses (for a profit).
While there are models of formal childcare for parents with atypical work patterns, the childcare market has failed to deliver such provision for working parents. There are a number of reasons for this, which we summarise in Figure 5.
It should also be noted that childminder numbers have been in decline, with 47,936 childminders registered in England in August 2015, compared with 61,428 in December 2008 (see Table 2). While some of this decline is a result of retirement, or childminders leaving to work in better-paid jobs, parental preference for group care accounts for much of the drop in numbers. Where childminders have been supported by networks, there is evidence that decline in numbers has been halted (Family and Childcare Trust, 2015b).
There are also signs of childminders adapting to changing circumstances, with a small increase in a type of provision termed 'childcare on domestic premises'. Here groups of childminders work together from the same domestic property, essentially acting as a small nursery. This provision gives the flexibility of childminding with the advantages of group care. However, there were only 211 providers of childcare on domestic premises in England in 2015, of which 52 were in London. The growth of this sector is slow because not all childminders have access to property of suitable quality and size, and because few areas have childminder networks, where potential business partners can meet. However, this is an area of business collaboration that could be expanded, potentially through the roll-out of childcare hubs, as discussed in Section Three.
FIGURE 5:
Reasons for gaps in childcare provision for parents with atypical work patterns
A diagram showing "THE CHILDCARE GAP FOR PARENTS WITH ATYPICAL WORK PATTERNS" at the center, surrounded by various reasons for this gap. Reasons listed are: - No local relatives/friends to provide care and reticence about asking acquaintances provide paid informal childcare - Childcare outside the office hours seen as a family responsibility - Poor quality childcare sufficiency assessment - Lack of trust in unknown carers who come to home - Unpopularity of workplace nurseries - Lack of information about local markets - Low profit margins for extended hours or at-home services - No start-up grants to develop new services
INNOVATIONS IN FLEXIBILITY
The availability of childcare solutions outside the nine to five pattern will only become more important as the economy creates more 'atypical' and/or unpredictable work. It is clear from the evidence above that the most successful innovations targeted at improving the flexibility of care - particularly for families with atypical work patterns or in need of occasional emergency childcare - will be focused on improving access to informal care. We see two primary areas for innovation:
- Strategies and platforms to build social networks for parents who lack social capital, in order to improve access to non-family informal care.
- The wider use of time-credits to reward and incentivise the provision of informal childcare.
CHILDCARE SOCIAL NETWORK
As discussed above, informal care often provides the best solution for parents who have ad-hoc, emergency and atypical childcare needs. But access to reliable informal care is heavily dependent on rich and established social and family networks. This can leave parents who lack such resources isolated and unable to access the childcare they require.
Digital platforms to promote reciprocal informal care have the potential to put interested parents in touch with each other, so they can then go on to arrange face-to-face meetings with a view to providing reciprocal informal care. At present no such site exists in the UK, although in the US there are a number of car-pooling and ride-sharing sites for children such as Zum and Shuddle that are demonstrating the potential for digital marketplaces to meet specific kinds of childcare needs. Here in the UK, platforms like care.com provide a marketplace for connecting formal childcare with parents, but the potential of the sharing economy to expand the pool of both informal and formal childcare provision has not yet been realised – particularly for parents living in disadvantaged areas.
IMPACT
Reciprocal childcare platforms have the potential to help parents build trusted social networks for informal and emergency childcare in areas where such networks are lacking. They could help overcome some of the social and class barriers to such arrangements that are explored above - enabling families in social grades D and E to access the sort of reciprocal arrangements that are more common higher up the socio-economic scale. This is particularly important as poorer families are more likely to be reliant on precarious contracts, shift work and other working patterns that can give rise to sudden or unpredictable childcare needs.
BARRIERS TO ADOPTION
Whilst digital platforms could be transformative in supporting better access to reciprocal childcare, there are a number of significant barriers to roll-out. These include
- Low likelihood of take-up in the target social groups.
- The cost of set-up and unclear revenue model.
- Ongoing questions of trust and confidence amongst parents.
NEXT STEPS
Overcoming questions of likely take-up and of trust and confidence may mean that a digital-first approach is not the most effective means of roll-out. Instead, it may be useful to look at existing spaces used by parents in target areas and use these as a jumping-off point. For example, organising babysitting circles that are built out of supermarket cafes, local leisure centres and/or existing formal childcare services may enable a provider to replicate the success of the NCT with a different target audience. Such circles could then be migrated online as trust develops. This means that such schemes are unlikely to be straightforward businesses and may instead be better facilitated by local authorities, other public service providers or charities.
Another example of how digital platforms could be used to improve informal childcare is Kindy App, in Australia. This easy-to-use app matches parents with pre-screened nannies, child minders and babysitters in their area. It provides parents with a mid-way between formal and informal care - giving them extreme flexibility alongside the confidence that comes with a third-party safeguarding process.
At present, such platforms have not taken off in the UK but they provide a much-needed answer for parents whose need for childcare is ad-hoc or unpredictable, and would help to plug the gap between the sort of reciprocal care detailed above and more formal childcare.
CARE CREDITS
Time-banking has the potential to catalyse and to reward informal childcare. Time credits are a form of alternative currency, where a credit is 'banked' for undertaking work or providing a service, then later spent on another good or service. Two hours spent picking up litter can be banked, for example, then later spent at a participating organisation such as a leisure centre.
CASE STUDY
SPICE
Spice create time credit systems in the public, commercial and voluntary sectors to ensure that time is valued and input reciprocated. For example, they support Haringey Council's drug and addiction outreach programmes by providing volunteers and mentors with time credits which they can then spend at a range of family and leisure facilities within the borough.
There are now nearly 300 time-banking schemes in the UK, although none that specialise in reciprocal or informal childcare. Time credits are also becoming more fungible, through the involvement of more organisations in these schemes, thus offering participants greater opportunities to spend their time credits.
Moreover, there are moves to increase the amount of personal care services through time-banking, in particular elder social care through the growth of schemes such as Care4Care. Here younger people bank hours of care for older neighbours which they can then use later, as their need arises, although there remain challenges about fungibility. Care4Care and similar schemes have built on the experiences of the Japanese Fureai Kippu time-banking scheme (Hayashi, 2012). Here credits earned for providing care for older people can then be used within the family group to 'buy' similar personal elder care services in another part of the country, or saved for later life.
Extending this Fureai Kippu model to cover informal childcare, parents could provide informal childcare to a neighbour and bank these hours of care. They could later spend their time-banked hours to 'buy' informal or formal childcare or any other good or service in the time-banking scheme. Recruiting large numbers of informal carers into a local time-banking scheme would overcome some of the fungibility problems.
In a country with high rates of residential mobility and where fewer children live in close proximity to their grandparents, there is also scope for using this model to increase the provision of grandparent childcare. The Smith grandparents living in Manchester could bank their hours of providing informal childcare to the Khan grandchild who lives next door. The Smith grandparents then transfer their time-banked hours to their own children in London, who use them to purchase informal childcare from another carer in their locality.
IMPACT
One in four families in the UK depends on a grandparent for help with childcare (Rutter and Evans, 2012), suggesting that where familial informal childcare is available it is not only taken up but often relied upon. In the UK, 10 per cent of households move home every year and around 1 per cent move to a new region. That means that every year 270,000 households arrive in an entirely new part of Britain, often leaving behind circles of friends and family - such as grandparents - who are able to fill informal childcare gaps. Additionally, net migration into the UK last year stood at 330,000 - including many families with children who have moved here to work. These families are precisely those who might stand to benefit most from time-banking schemes that allow them - or relatives elsewhere - to earn childcare credits that can be spent to meet their own childcare needs later on.
BARRIERS TO ADOPTION
The primary barriers to adoption of time-banking schemes are attitudinal and developmental. Participants may be worried that time credits are not fungible or useful, leading to low take-up. And designing a platform that works well, is secure and easy-to-use requires both skill and investment.
NEXT STEPS
There has been tacit support for time-banking from the main political parties, although little by way of real strategy and with no reference to informal childcare. If time-banking is to be used to catalyse reciprocal informal childcare, kick-starting by central government is probably needed. This is required to support the greater involvement of time-banks in reciprocal informal childcare and encourage national co-ordination to ensure fungibility. A national marketing and information strategy is also needed, to inform parents about Ofsted-registration and safety and to challenge attitudinal pinch-points about informal childcare.
CONCLUSIONS ON FLEXIBILITY
Flexibility is often the missing link when it comes to government interventions in childcare, which tend to focus on formal childcare. But parents will always rely on a blend of formal and informal, flexible care.
Catalysing informal and reciprocal childcare can be done with relatively little expense compared to many other interventions in the childcare market. By actively facilitating new social networks amongst groups of parents and supporting the extension of time-banking for reciprocal care, local and central government can play an effective role in helping build informal childcare capacity within communities.
SECTION SIX:
CONCLUSIONS AND RECOMMENDATIONS {: #section-six }
Childcare provision is a crucial part of a modern state's infrastructure: it enables parents to work, improves children's outcomes and helps narrow the gap between disadvantaged children and their peers. Recognising these benefits, all recent governments have committed to increasing the supply of childcare, making it affordable and improving its quality. While much progress has been made towards achieving these policy aims, high childcare prices remain a significant barrier to work for many parents, and there are many gaps in provision. Both of these factors are barriers to employment for parents, primarily mothers. At the same time, profit margins are tight for many private providers, who deliver the majority of daycare in England. Finally, the regulated free market has failed to deliver care that is flexible enough to meet the needs of shift workers, freelancers and others with 'atypical' work patterns.
Some of these issues might be expected from a relatively new addition to the care and education sector: as late as 1990, there were just 59,000 nursery places in England and Wales, compared with over 1.8 million places today. But there is now an urgent need for innovation that could address problems such as high prices for parents, low profit margins, gaps in provision and a lack of flexibility in delivery.
The research for the project has enabled us to shortlist four areas that have the potential to deal with England's childcare 'pinch-points'. These are:
- Co-produced childcare: bringing more appropriately-trained volunteers and parents into formal childcare settings in order to reduce staffing costs, expand the social mix of adults in childcare settings and reduce costs to parents and families.
- Provider collaboration: bringing childcare providers together to share premises, facilities and back-office staff to reduce these input costs, as well as to develop new forms of provision such as childminder hubs and childcare on domestic premises.
- New forms of investment and funding: leveraging new investment into the child-care market - particularly in deprived areas.
- Informal childcare social networks: increasing participation in reciprocal informal childcare networks through care credits; expanding the reach and take-up of digital platforms to match supply and demand easily and flexibly.
If these new models of childcare are to be developed and scaled they will need support from local and central government, from childcare providers, from social and private entrepreneurs, from civil society and from parents.
To that end, we offer the following recommendations, aimed primarily at central and local government, but also at childcare providers and innovators.
- Central government should embrace the need for innovation in childcare and work cross-departmentally - specifically bringing together the DfE, DWP and HMRC - to develop a coherent childcare strategy. This strategy should:
- Identify innovative practice nationally and internationally, assess the impact of that practice and develop a strategy for implementing and scaling that practice in the UK.
- Encourage and set out a pathway, in collaboration with local authorities, to encourage and develop parent and non-parent volunteer involvement in childcare settings. This pathway should include providing frameworks for training volunteers, for quality assurance, and for safeguarding.
- Provide seed funding for an organisation to support parental co-produced childcare settings, similar to the Parent Co-Operative Preschool Corporation or the New Schools Network.
- Encourage childcare providers to collaborate (for example by forming small chains or sharing premises and back-office functions) and provide tangible incentives, such as tax breaks and access to funding, for them to do so.
- Bring together a range of funders from across sectors to explore opportunities for social investment into the childcare sector, where the broader economic, social and education outcomes of expanding childcare into areas of under-provision can be understood and quantified.
- Pilot and assess models of direct provider funding in local authorities where the need for increased childcare provision is most acute.
- Provide seed funding for new childcare and childminding hubs, possibly drawing on local, underused assets such as libraries or other public buildings.
- Central government should commit to being a strong advocate for an expanded mix of proven models of childcare, including volunteer involvement, childcare on domestic premises and care credits/timebanking, to ensure there is public buy-in for such models, especially among parents.
- Central government should direct its funding and support towards the 57 per cent of local authorities which report not having sufficient childcare provision.
- Central government should reverse the policy of local authorities as 'providers of last resort' and allow local authorities to develop their own childcare provision, which is generally cheaper than private or not-for-profit provision.
- Central government and local authorities should encourage volunteering hubs (such as CVSs) and platforms (such as Do-It or Team London) to embrace and encourage volunteering in childcare settings.
- Childcare providers should:
- investigate ways in which they can collaborate to save on costs including premises, back-office functions and staffing.
- Consider volunteering not only as a solution to high staffing costs but also as a positive addition to childcare settings, and develop strategies for involving volunteers in their service delivery.
- Examine, assess and implement innovative, proven models for increasing profitability and economies of scale including cross-subsidies and out-of-hours home-based care.
- Innovators should:
- Examine and develop the potential for apps and digital platforms to better match supply and demand of informal childcare to support an increased mixed model of provision.
- Develop strategies and platforms to build social networks - digital or not - for close relatives or friends who can offer informal childcare.
Taken together, these ideas hold the potential to transform the childcare market by reducing the cost and improving the accessibility of safe, quality childcare while ensuring that new childcare solutions develop to respond to our more flexible labour market.
Politicians across the spectrum have recognised the need for government to play a role in supporting parents who want to re-enter the workforce and improving children's life chances. We have progressed by leaps and bounds over the past two decades, but now is the time to take the next step and to look seriously at how we can not only support the existing market but also support it as it grows and evolves to meet the challenges of the present and the future.
BIBLIOGRAPHY
Butler, A. and Rutter, J. (2015) ‘Access denied: A report on childcare sufficiency and market management in England and Wales.’ London: Family and Childcare Trust.
Department for Education (DfE) (2012) 'Childcare Providers Finances Survey.' London: DfE.
DfE (2014a) 'Childcare and Early Years Parents' Survey 2013.' London: DfE.
DfE (2014b) 'Childcare and Early Years Providers' Survey 2013.' London: DfE.
DfE (2014c) 'Early education and childcare: statutory guidance for local authorities.' London: DfE
DfE (2014d) 'Statutory framework for the early years foundation stage.' London: DfE.
DfE (2015) 'Review of childcare costs: the analytical report.' London: DfE.
Family and Childcare Trust (2015a) ‘Annual Childcare Costs Survey 2015.' London: Family and Childcare Trust.
Family and Childcare Trust (2015b) 'Waltham Forest Childcare Sufficiency Assessment.' Unpublished report to Waltham Forest Council.
Family and Childcare Trust (2016) 'Annual Childcare Costs Survey 2015.' London: Family and Childcare Trust.
Hayashi, M. (2012) Japan's Fureai Kippu Time-banking in elderly care: origins, development, challenges and impact in 'International Journal of Community Currency Research.' Vol 16: pp.30-44.
HM Government (2014) 'Growing the Social Investment Market, 2014 Progress Report.' London: Cabinet Office.
Maughan, C., Rutter, J. and Butler, A. (2016) 'In for a pound: The relationship between staff wages and Ofsted grades in group-based childcare provision.' London: Family and Childcare Trust.
House of Lords Select Committee on Affordable Childcare (2015) 'Affordable Childcare.' London: The Stationery Office.
Nicholls, A. (2010) ‘The landscape of social investment in the UK.' Birmingham: Third Sector Research Centre, University of Birmingham.
Rutter, J. and Evans, B (2012) ‘Improving Our Understanding of Informal Childcare in the UK.' London: Daycare Trust.
Smith, T., Coxon, K. and Sigala, M. (2007) 'National Evaluation of the Neighbourhood Nurseries Initiative: Implementation Study.' London: Department for Education and Skills
Nesta
1 Plough Place London EC4A 1DE
July 2016
Nesta is a registered charity in England and Wales with company number 7706036 and charity number 1144091. Registered as a charity in Scotland number SCO42833. Registered office: 1 Plough Place, London, EC4A 1DE.
Footnotes
-
In this report we draw upon data produced by different government departments whose jurisdictions differ because certain areas of policy are devolved. We have focused on England in this report, but sometimes use data representing England and Wales or the UK as a whole. ↩